

At a crossroads: is it code red for the metal of the future?
- 13 September 2025

Copper is “poised at the centre of a tug‑of‑war between near‑term macro‑economic headwinds and long‑term electrification and AI tailwinds”, one veteran mining analyst said this month. Another highlighted a “massive decision to be made collectively by the Western world” about the red metal. Resourcing Tomorrow, coming soon, will fittingly probe whether copper is at a crossroads.
The December 2-4 event in London will bring together a host of the world’s copper leaders – including from Codelco, BHP, Rio Tinto, Hindalco Industries and the International Copper Association – to talk about copper supply in an era of unprecedented demand for the metal.
Barrick Mining CEO Mark Bristow will weigh in. Barrick is developing one of the world’s biggest new copper mines in Pakistan and funding a major expansion in Zambia. “We are seeing a shortage in supply, and growing demand particularly with the data centres, the movement to cleaner energy, and just generally as the emerging markets start investing in industrialisation, which is a big consumer of copper," Bristow said recently in Lusaka. “So, everyone is in agreement that the copper demand is outgrowing the supply side.”
Veteran analyst Ken Hoffman says he’s been looking at copper markets for nearly 40 years.
“In a way, the copper market has been driven by a few fundamental factors: the rise of China, the US consumer, and supply challenges that can cause significant disruption,” says the former global head of battery materials at McKinsey & Company and now commodity strategist with Canada’s Red Cloud Securities.
“As always, there are deficits in the future, but overall prices move higher over time.
“But 2026 is looking different.
“Copper will face a highly volatile 2026 due to dollar woes, tariff tantrums, weak economies and massive AI grid investments.
“US trade war tariffs and economic slowdowns will likely reduce copper demand growth in 2025–2026, potentially creating a small surplus. However, the explosive growth of clean energy, grid battery storage, electric vehicles and AI data centres – supported by credible projections from the International Energy Agency [IEA], Bloomberg NEF and industry sources – suggests that global copper consumption will accelerate from 2027 onward.
“Supply constraints, long permitting timelines and the risk of disruptive events mean that any short‑term surplus could quickly flip into deficits.
“Policymakers and investors should therefore prepare for volatility: fostering domestic production and recycling to alleviate supply risks, while recognising that copper’s role in the energy transition and digital economy makes it a critical material for decades to come.”
One country has so far prepared for that volatility and for copper’s increasing strategic importance far better than any other.
John Forwood, chief investment officer at Australia’s Lowell Resources Funds Management, says China accounts for a staggering 60% of global copper consumption today.
“So what happens in China is seriously important for the copper market,” he says.
China accounts for 8% of global mined copper production but 44% of global copper refining capacity. That compares with only 5% in the USA, which wants to seriously scale up both mining and refining to feed escalating domestic demand.
Forwood said smelter treatment charges were currently “basically zero or negative because of the competition in China for copper concentrates”, a situation that was unsustainable for other refineries, including in Australia. He said: “There’s a massive decision to be made collectively by the Western world: do we want to allow China to take over copper refining and become like, say, rare earths, or do we put massive money behind the treatment industry to help retain some independent supply?”
Forwood says while long-term charts show increases in copper demand being “absolutely inexorable” over decades, possible expansion from circa-28Mtpa this year to more than 40Mt in a decade presents some real challenges for the world given past supply growth rates (see the chart below) and the outlook for new supply. The IEA suggests copper recycling rates - currently below 20% compared with 80% for aluminium – will step up, but nowhere near enough.
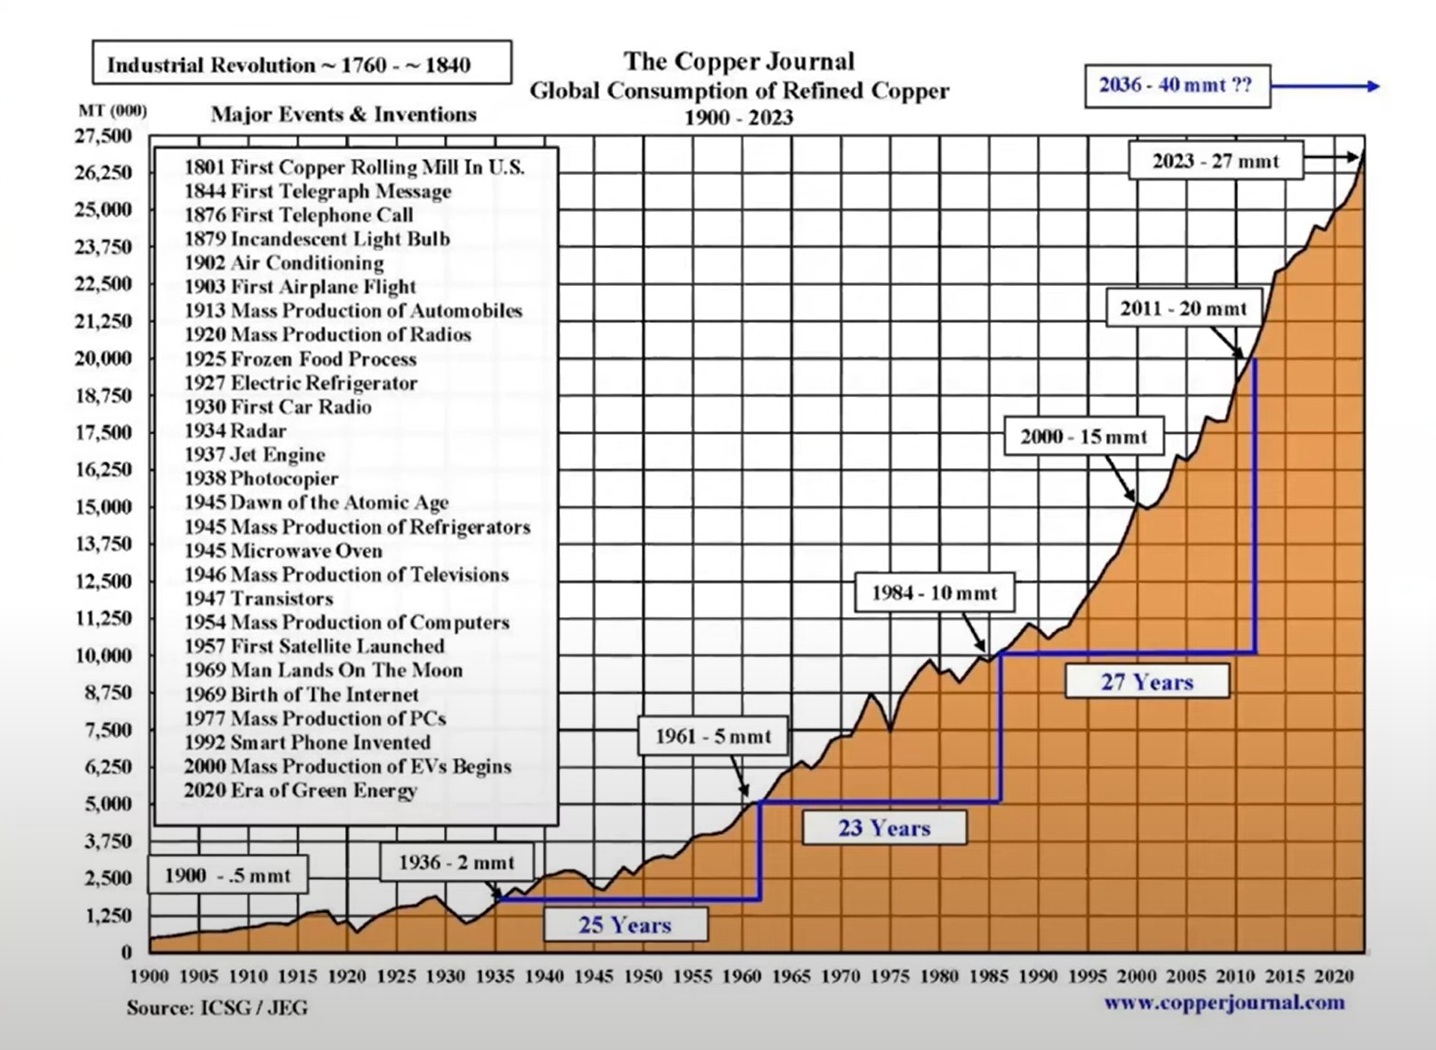
“That means new mines are required,” Forwood says.
Hoffman says copper supply “has been and likely always will be a challenge”.
“On the supply side the long lead times for new mines – nearly 30 years in the US – and recent production setbacks indicate that supply is unlikely to keep up with accelerating demand,” he says.
“The Trump administration plans to drastically reduce this time to market but even so major new supply in the US is likely a decade away. US copper output fell 3% in 2024 following an 11% decline in 2023.
“Panama’s closure of the Cobre Panama mine removed 350,000 tonnes of annual supply in late 2023. Codelco has seen a number of issues with production and could be the biggest wildcard in 2026.
“Even the modest 289,000t surplus forecast by the International Copper Study Group for 2025 could vanish quickly due to disruptions. Therefore, unless investment in mining, recycling and substitution rises sharply, the market could transition from surplus to deficit by the late 2020s.
“Supply growth is fragile even before considering surging demand.”
Nowhere is the crossroads analogy more apt than the US, which has an estimated 48 million tonnes of identified copper resources but only three operating domestic primary smelters.
In Arizona, where joint venture partners BHP and Rio Tinto have taken circa-25 years to not yet get their proposed multi-billion-dollar Resolution copper project permitted, Gunnison Copper recently switched on its new Johnson Camp mine which it is aiming to ramp up to a modest 25 million pounds per annum in 2026. With other skarn copper deposits presenting along an 8km (at least) trend, including the company’s flagship Gunnison project, it wants to grow production and launch a deeper search for porphyry copper – potentially in partnership with Rio.
“We’re really in a great time for copper and to be producing copper in the United States,” Gunnison Copper CFO Craig Hallworth said this month.
“Copper is going into virtually everything that’s important today. You can’t go two seconds without someone talking about artificial intelligence. And guess what AI needs a lot of? It needs lots of copper. There’s about 27 tonnes of copper in every megawatt of applied energy that goes into a data centre. And AI is completely dependent on new data centres coming to market. Every single data centre could use millions of pounds of copper.
“So we’re going to see an enormous increase in demand in the US and that’s why we’re well positioned at Gunnison Copper as the newest producer to be supplying copper directly into those supply chains.”
Hoffman says while trade war and tariff collateral damage could lower short-term copper demand in parts of the world, particularly North America, “this will be offset by a huge shift in electrical grid build, as stationary storage – now more than 60% of the size of the EV market – growth is to exceed 50% after several years of more than 100% growth”.
“This explosion of BESS [battery energy storage] systems is to meet all of the infrastructure needs given the super-cycle growth of AI data centres, which could account for more than 10% of all North American electricity demand within five years,” Hoffman says.
“Overall, the AI side effect impact on global grid needs will push millions of tonnes of new copper demand.
“We can see the AI server farm electrical impact in the US data, where electricity demand has risen by 14.2% in 2025 year-to-date through August, according to the Edison Institute.
“Overall electricity output in Europe and North America has been on a very slow growth trajectory, averaging less than a compounded 1% over the past 25 years.
“AI changes all of this. Server farms use tremendous amounts of electricity. For example, the soon-to-be-built mega server farms in the UAE will use as much power as four million US homes: 5GW.
“The downside of a huge build-out in server farms was seen in Spain, which has the most server farms in the EU. On April 28 of this year the Iberian Peninsula blackout occurred, in which nearly the entirety of Spain’s and some of Portugal’s electrical grid collapsed. While the blame was put on renewable energy becoming too big a part of the grid supply, the cause of the demand spike was made worse by the huge demand for electricity by server farms.
“In light of this collapse it was found that the building of massive back-up reserves of electricity, through battery stationary storage, was needed. The size and scope of what is needed by the global grid, we believe, is being underestimated.
“But the demand for copper from this AI push is already being seen in battery production numbers, and those numbers are staggering.
“Already in 2025, an estimated $200 billion will be spent on server farms, and that number could rise into trillions of dollars by the 2030s, according to McKinsey & Company.
“Copper’s exceptional electrical and thermal conductivity make it indispensable to power generation, transmission, and digital infrastructure. Transmission lines, transformers, motors and renewable‑energy technologies rely on copper wiring and components.
“The transition to low‑carbon electricity and the explosive growth of AI data centres intensify this dependence.”


