

BMI expects 2026 mining deal count to rise
- 7 February 2026

London-based BMI has added its voice to predictions of a rising global mining and metals M&A tide in 2026. It also expects big miners to maintain a quality over quantity approach to capital deployment on significant projects.
“We expect robust M&A momentum across the metals and mining sector to continue in 2026, fuelled by the accelerated race for critical minerals, with industry players prioritising opportunities that strengthen their exposure to minerals essential for the energy transition,” commodities analyst Amelia Haines said on a BMI webinar addressing this year’s mining and metals key themes.
Copper, lithium and rare earths topped this list.
“At the same time we expect the biggest miners to maintain a stringent stance towards capex in 2026, adopting a cautious approach to the mid-term demand and price outlook, with sizeable capex being favoured for high-quality projects.”
Haines said the group’s country risk intelligence suggested “broad tariff uncertainty” was likely to decline in 2026, though “we could see flare-ups between the US and individual economies”.
“This will support demand for commodities in general,” she said.
“We do not rule out bouts of volatility, especially as certain metals might face renewed US tariff pressures to protect critical domestic industries. In particular, copper remains on the cards for further tariffs.”
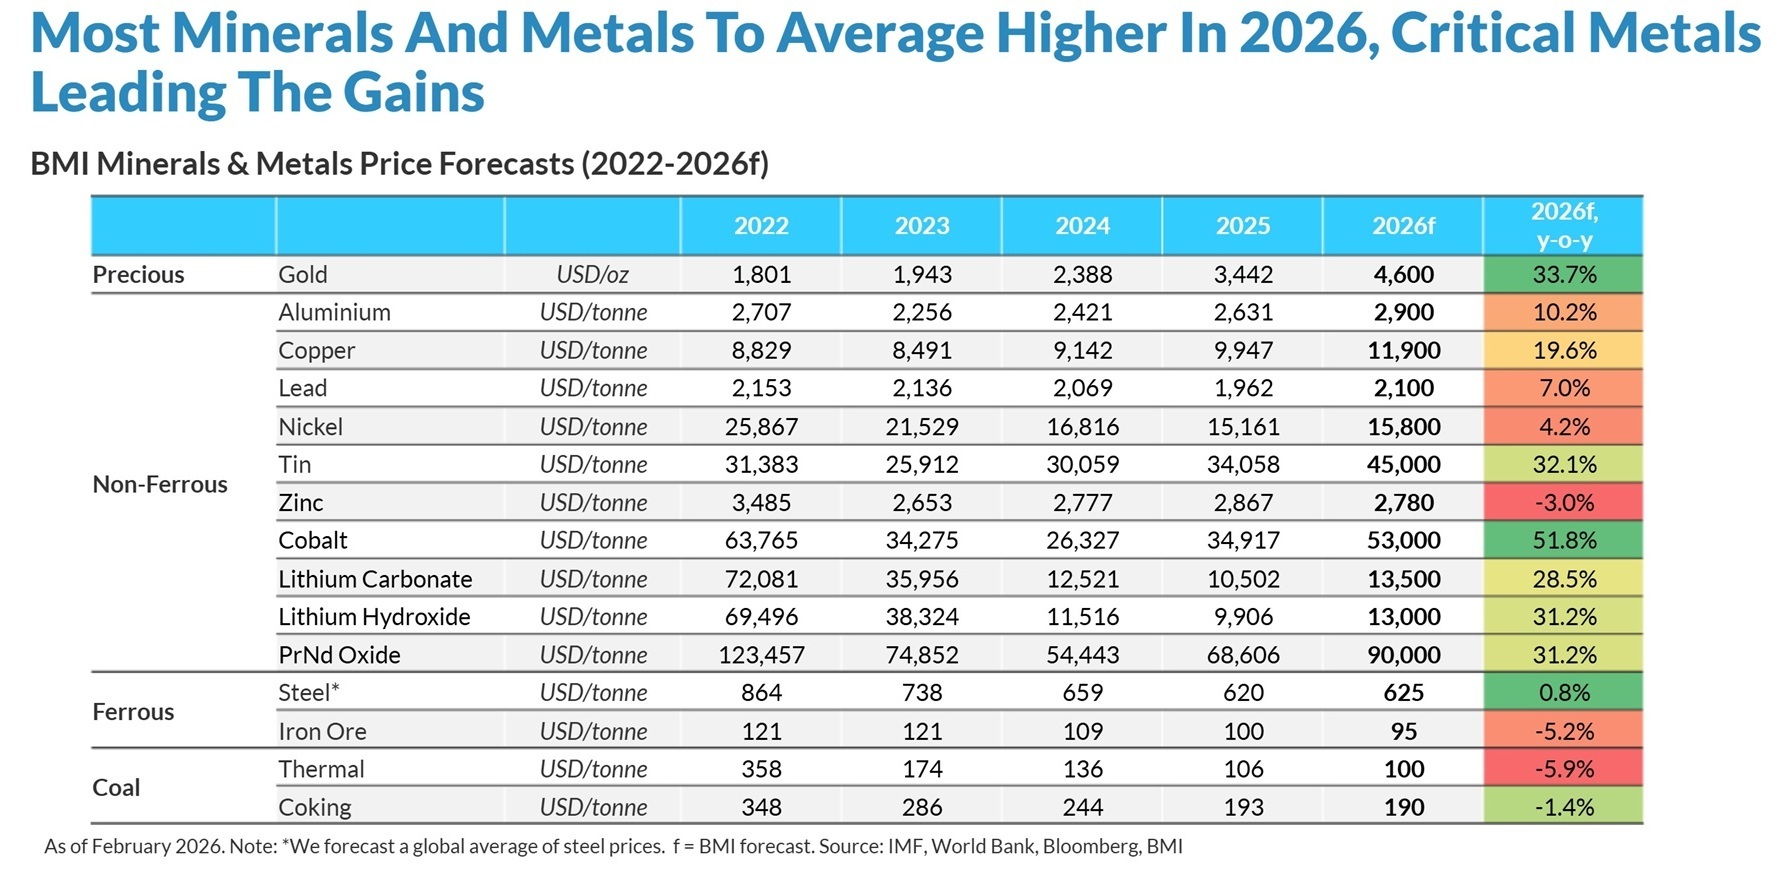
More broadly, resource nationalism is seen as “the primary risk” facing mining and metals investors in 2026 as resource-rich “frontier markets” jostle for more substantial Western investment and security initiatives are scaled up.
“Sub Saharan Africa, in particular, is poised to be one of the stronger performing frontier market regions in the coming years,” Haines said.
“The DRC is set to lead, reflecting its significant mineral resource base, with copper a key driver. However, [BMI analysis] also highlights that markets across the region rank poorly in our operational risk index.
“Throughout 2025 a range of developments underscored the rising risk of resource nationalism in particular, and particularly the growing use of export bans as a policy tool, including the Democratic Republic of the Congo's introduction of a ban on unprocessed cobalt exports in February 2025 which was later replaced with a restricted quota, and Malawi's decision to prohibit the export of all unprocessed minerals in October 2025.
“We’ve already began to see this trend follow us into 2026 with Ghana introducing an export ban on unrefined gold just a couple days ago, mandating that all gold be refined domestically, as it looks to increase in-country value addition and capture a greater share of the sector's downstream margins.
“While overall production is expected to continue, heightened risks could push major miners to scale back or exit these markets. Glencore has recently announced the sale of stakes in several African assets as part of a broader effort to de risk its portfolio, reflecting a more cautious approach to operating in politically complex frontier markets.”
History shows export curbs on unprocessed materials is a double-edge sword. Indonesia’s 2020 ban on raw nickel exports triggered a foreign investment boom in domestic processing and refining. Haines said more than 70% of global cobalt supply came from the DRC, with Indonesia looming large in this small but growing world market.
“The DRC's recent export ban has driven a sharp surge in cobalt prices,” she said.
“We now expect prices to average US$25 per pound in 2026, up more than 50% from the 2025 average.
“This reflects the DRC's decision to cap cobalt exports at roughly half of typical annual production, which is expected to leave global cobalt supply materially below 2024 levels, falling for at least the next three years.
“In the case of cobalt, however, we expect higher prices to drive demand destruction downstream as battery manufacturers accelerate efforts already underway to reduce or eliminate cobalt content in battery chemistries.
“At the same time, we expect the DRC's influence over the global cobalt market to diminish as Indonesia continues to ramp up its exports.
“Cobalt is an extreme example [that] illustrates a broader dynamic.
“The greater a country's share of global supply, the more leverage it has over the market, and the greater the price impact when supply is constrained. However, that same price response also amplifies the demand side reaction, ultimately limiting the durability of that leverage.
“Export restrictions in these markets therefore need to be finely balanced, encouraging local processing without pushing downstream consumers to reduce demand or switch to alternative supplies.”
Haines said BMI also expected more metals and mining projects to benefit from partnerships with tech, auto and aerospace companies in 2026.
“The supply of critical raw materials will be a growing priority for industry players and end users over the coming decade,” she said.
“Another wave of demand is also set to come from AI and the AI and defence sectors.
“Industrial policy is becoming central, driving metal prices, notably for critical minerals, which are also increasingly viewed as strategic assets and central to governments’ national priorities. We expect this trend to continue and only accelerate as we go throughout 2026, ultimately translating into sustained upward momentum for metals.”


