

IMARC 2025: 10 vital conversations (Part 1)
- 5 December 2025

A well-timed US-Australia minerals deal, gold and silver price volatility, and slowing world economic growth were in the headlines during this year’s International Mining and Resources Conference + Expo (IMARC) in Sydney, Australia. Digging a little deeper, though, there were at least 10 major themes to come out of the 2025 edition of one of the world’s major annual mining investment, trade and technology forums.
- China, not surprisingly, figured in many event conversations. A common question asked was, how does the West, in particular, “catch up”, or restore its leadership, across vital supply chains? It seems to presume China will stand still, which IMARC audiences heard was unlikely.
- The US is absorbing a lot of the world’s attention – for a variety of reasons. But another part of the world remains its primary growth engine and it’s hard to see what could change that.
- EY’s list of top 10 mining risks for 2026 has operational complexity as No.1. IMARC probed operational complexity from all angles and, ironically, some simple solutions resonated most.
- Australia has been labelled, rightly or wrongly, the lucky country. With its prosperity this century underwritten by iron ore, coal, LNG and other commodity exports, it now finds itself at a crossroads. Concerns, lots of them, were raised about the country’s ability to come together on a path to continued prosperity.
- Strong post-COVID ESG “signalling” by corporates (and governments) has been somewhat muted by Trump 2.0 and other factors. But the mining industry, broadly, knows it must be better or it will continue to struggle to regenerate project pipelines and build new mines at sustainable capital intensity levels. IMARC dived deeply into where and why this improvement must occur.
- For a few years now “smart mining” has referred to the digital and automation undercurrents starting to shift the industry’s operational focus. However, as IMARC 2025 amply demonstrated, it is becoming a much broader and more urgent discussion than it was when the term was coined.
- Public-private partnerships are key to rapidly reshaping new ex-China mineral-based value chains. That ball is rolling in countries such as Saudi Arabia and also now in the US, Australia and Europe. Where and how it lands will be watched very closely up to IMARC 2026.
- The industry is spending more freely on digital and sensing technologies and a large number of start-ups are pouring into the space. The big dollars being paid for acquisitions show where the “smart money” is going. But is the industry investing enough in innovation and technology and is it another area where China is simply moving faster?
- “People are our most important asset/resource” is a favourite mantra of company marketing departments. In mining, kneejerk responses to predictable (and predicted) commodity price cycles and the ongoing hollowing out of Western mining academia jar somewhat with the rhetoric.
- “Critical minerals” are taking all the headlines but while gold seems to be one of the few metals left off lengthening country critical mineral lists it continues to dominate exploration budgets and get most investor attention. This is not a cyclical phenomenon, it’s an evergreen trend. When mining, broadly, is supposed to be capital, people and generally resource-constrained, what does that mean?
Long-term view trumps pendulum swings
Traxys CEO Mark Kristoff said recognising a problem was a crucial step in solving it and on that score the veteran metal and commodity trader is satisfied the West is now at least wide awake to the challenges presented by China’s dominance of critical materials and downstream supply chain.
The US-based Centre for Strategic and International Studies says in the past 30 years China has become “a dominant” world player in mineral supply chains that are key to US (and European, etc) national and energy security. “Even if it is a marginal producer directly, China finances and imports from the rest of the world to control 65-to-90% of global supply of key metals. This concentration is the result of decades of industrial strategy and foreign policy from Beijing,” CSIS says. “It is also a strategic challenge for the United States, given the importance of strengthening national security and meeting energy needs while geopolitical tensions between the two countries rise.” Moreover, China has developed “a robust workforce that has allowed it to develop an absolute advantage in these supply chains”.
That encapsulates the “problem”. The really big question is, can the US and more broadly the West address it as China continues to leverage the vast scale and diversity of its now fortified industrial value chains to provide more of the products the world needs and build out new industries?
“We [Traxys] started talking about what the Chinese were so successfully doing 20 years ago in taking the whole value chain and creating pinch points where they could basically become champions with their 10-year capital return models, combating a 90-day Western capital return where the CEO running a company could not afford to operate at a loss for long enough because he was ousted,” Kristoff said.
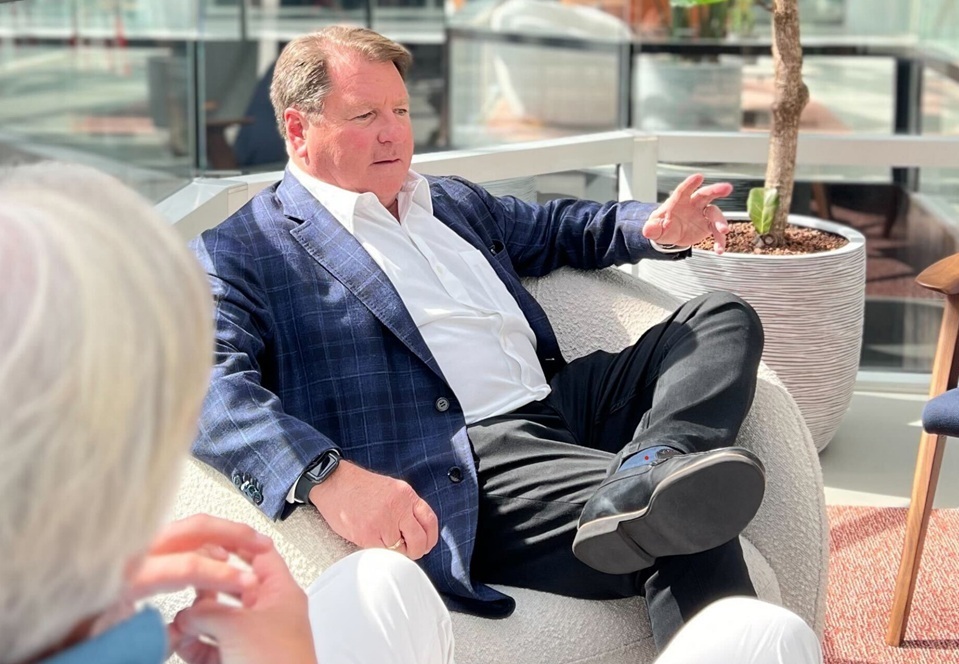
“We’ve [still] got a fundamental problem with the duration of capital investment. We then also have a problem with the cost of capital. The Chinese have been very effectively subsidising industry with very cheap money: 5% debt doesn’t compare with 2% debt.
“So we need to come up with the right structures. And I think that’s started.
“Permitting is a big part of the government equation. If it takes seven years to permit a project in Australia or the United States or western Europe and you can do it in 18 months in China that is not an effective tool.
“But I'll come back to the basic building blocks of competitive business. We need a competitive cost of capital that should be supplied by government initiatives if we want to compete with the low cost of capital around the world, which has been China historically; the Japanese and the Koreans, to an extent, have also done it. The West has failed miserably in providing capital for extractive industries, or perhaps transformational industries, and we have to fix that if we're going to bring these solutions to bear.”
Mark Compton, executive director of the American Exploration & Mining Association (AMEA), told an IMARC audience overall US mining policy in the nearly 30 years since the country shuttered its national mines bureau could be described as a program of benign neglect “that has led to [substantial] mineral import reliance”.
“The Biden administration said a lot of the right things when it came to the need for more domestic mining and secure domestic supply chains, but ultimately the actions that they took on the ground were decidedly anti-mining,” he said.
“We now have the Trump administration in. They are obviously unabashedly pro-resource and development and really hyper focused on minerals and minerals supply chains.
“[But] the pendulum swings that we see from administration to administration really have been a barrier to advancing the mining and mineral processing industries in the US.
“It’s not unique to mining but we are also a very litigious society in the US and we have to deal with what I term the environmental industrial complex. You have environmental organisations whose entire business model is based on pursuing resource development projects in that permitting phase.
“And then – and this is keenly true in the United States – we really have a workforce crisis. It’s been estimated that half of the mining workforce in the US will be eligible to retire in the next five years. That is a very daunting statistic and we’re not training folks that we need, whether it’s in the industry or government. To permit projects in a more timely manner they need a skilled workforce that understands mining.”
Dominic Raab, former UK deputy prime minister and now head of global affairs at Appian Capital Advisory, said social license for industry, capital formation and allocation, certainly election cycles and even the framing of success or failure, all distinct paradigms in the current geopolitical landscape, were indicators of a more fundamental divide.
“One of the challenges I think we’ve – the West – got compared to China is we just don’t take a long enough view of the world,” he said.
“I look at China and I think that they have an ability to plan, a concentration span and a staying power which we ought to look at and be quite envious of.
“There is a real concentration span challenge for government but also for business [in the West].”
Russell Delroy, founder of Western Australia-based Nero Resource Fund, said: “Ultimately somebody’s got to sell a good at a price and it’s got to be competitive.
“And if you look at, say, Chinese automotives, they were an irrelevance five years ago. They’re now the world’s largest auto exporter. The cost of the final good is partially a function of the cost of the inputs so the cost of the inputs have to remain low and China is wiping the floor with us.
“And how are they doing it? Scale, without question, throughout the value chain. But even in mining and mineral processing they're doing it with scale. They're doing it with low-cost reliable power and specifically within nickel, as an example or a case study, they’re doing it in a dynamic where the regulatory risk is low. It’s pre-permitted. All the tape, however you want to define it, is dealt with so there’s no risk.
“You can turn soil tomorrow and if they start tomorrow they’ll build a nano-factory within nine months.
“The direction of travel here is also a problem because 30 years ago you could have said, yeah, but they don’t know what they’re doing and they're going to copy us and maybe they’ll get there. Well, that’s already happened.
“Now they own all the tech in mineral processing. We don’t do it. We told ourselves we’re clean and green and the West doesn’t do all that filthy stuff anymore. And if you go to war, that might be a problem.
“There’s growing awareness around this but we’re not having conversations about the fundamental problem.
“The fundamental problem is cost. Cost is a function of regulation and power. They’re the two key drivers.”
Asia in the driver’s seat
US data centres, manufacturing and electromobility are certainly going to help fire demand for some rare earth elements, copper, uranium and lithium over the next decade. But urbanisation, including faster electrification, in Asia will remain the primary driver of commodity demand and ultimately the pricing that will dictate rates of investment in new mines and downstream metal production.
“If we start with demand – long term, big picture – there are two key dynamics,” said Nero’s Delroy, who cited research by Hong Kong-based Gavekal.
“[They are] ongoing urbanisation in Southeast Asia ... and AI and humanoid robotics. That’s a 10-year view. We can all talk in the short term but long term, there’s very little debate about robust demand, in my view.
“[In SE Asia] there’s big urbanisation numbers – a billion-plus [people] – still to occur.
“It’s incredibly commodity intensive.
“If you then go to supply, Western supply, in particular, is a drama.
“Why is it a drama? Because we’ve moved from a unipolar dynamic to multipolar dynamic. It’s not coming. We’re in it right now. China is a superpower right alongside the US. And as such, suddenly there’s awareness around supply problems in the West. For 30 years we’ve effectively de-industrialised processing of raw materials and we now are slowly waking up to what that means.
“It’s most pertinent in rare earths ... but it’s way broader than that. It's 60% of aluminium, 60% of iron, 50% of zinc: they're all processed in China, so they dominate that landscape. It’s deeply uncomfortable for the West.”
Appian Capital’s Dominic Raab said Chinese ambitions across metals and connected manufacturing value chains were “off the scale”.
“If you look at China’s increasing dominance, first of all, they’ve got a really good strategy. Let’s not pull our punches. They’ve got a smart strategy; huge innovation. Of course, they avail themselves of all of the tools of command economies and they’ve been doing it for 20 years.
“But they’re going right the way across the value chain – refining, processing, but also battery dominance, manufacturing and wider areas in the industrial base.
“If you speak to Chinese investors now and ask them what they’re procuring it is pretty much everything.
“We’re well behind. But to avoid the doom loop ... there’s lots of things we can do about it.
“At Appian Capital we have delivered 12 mining projects since 2016. That’s more than the top five mining companies combined. So pick your partners well.
“And the Trump-Albanese deal was fascinating: $3 billion invested from government capital to unlock $50 billion worth of [private] investment. That’s the kind of thing we need. We need better public-private partnerships and friendshoring if we’re going to meet the range and volume [of materials] that our industrial bases sorely need. Governments are not great at picking winners but they can pick good public-private partnerships.”
In its latest copper whitepaper “tigers to titans” view of Asia, Wood Mackenzie says India and Southeast Asia are “just warming up on the economic development front”. Their industrialisation could add 3.3 million tonnes per annum of copper demand by 2035. “However, if they see even half of China’s development trajectory the construction industry alone would require an additional 3Mtpa of copper, with electrical networks adding another 2.4Mtpa,” the UK-based research and consulting firm says.
“Critical” mineral lists have grown and grown but copper, iron and aluminium are the world’s bellwether mineral commodities. WoodMac vice chair of metals and mining, Julian Kettle said at IMARC: “The challenge we have around supply chains isn’t just about some of these really funky metals that many of us couldn’t pronounce the names of five or 10 years ago. It relates to basic commodities – aluminium and copper, to name but two. Because if you think about the direction of travel over the last 20-to-25 years we have flatlined at best in terms of our supply chain position and in many, many of the commodities we’ve actually reduced our self-reliance on those commodities.”
The long-term potential for copper growth was locked in, WoodMac’s report said. “But the convergence of electrification, AI infrastructure, defence spending and Asian industrialisation all create multiple paths to an explosion in demand. In a supply-constrained market, however, timing is everything – and various indicators point to simultaneous acceleration in numerous sectors.”
WoodMac says while China’s steel industry, which grew by 50% between 2010 and 2023, is expected to contract significantly by 2050 due to declining domestic demand, regional steel production expansion was picking up. “India and Southeast Asia are emerging as growth powerhouses,” it says. “India is expected to nearly triple its steel production by 2050 to become the second-largest producer globally.” Vietnam, Thailand and Indonesia would lead significant Southeast Asian growth.
News flash: Mining’s getting more complex
Operational complexity came out of nowhere to top this year’s EY top-10 list of global mining industry risks – having not made an appearance previously – and on the evidence presented at IMARC it won’t be going anywhere. EY said after last year’s survey of miners for the annual risk outlook list and report that capital constraints, low discovery rates and slow project permitting all added “complexity to the situation”. The situation being a simple but unsettling prospect: “Over the next 30 years we will need to mine more than we have over the last 70,000 years” to achieve global decarbonisation targets and energy transition goals.
Notwithstanding the gravity of that situation, miners found themselves caught in a paradox, said ERM critical minerals global director, Toby Whincup. “While demand for minerals is skyrocketing—driven by energy transition and energy security, defence needs and accelerating technology and AI—the pace of new mine development has slowed to a trickle,” he said.
“Miners are forced into more remote, lower-quality deposits, facing volatile prices and a legacy of public mistrust.”
Wood Mackenzie alluded to other layers of complexity in a report released on the eve of IMARC.
“Beyond structural financing and geopolitical challenges, physical supply disruptions are an escalating concern,” it said.
“The industry’s move towards underground mining over the next two decades underscores the significant technical and cost hurdles involved. Codelco’s Chuquicamata is one example where an extraction ramp-up has been pushed back a full decade to 2040 due to engineering setbacks, geological challenges and pandemic-related maintenance delays.
“Safety risks add another layer of complexity.
“Recent incidents at Grasberg, Kamoa-Kakula and El Teniente highlight the dangers of deeper, more intricate underground operations. At the same time, some producers are experimenting with sulphide leaching – a technology with a limited commercial track record – as an extraction method, raising questions about long-term reliability and output stability.”
EY global mining & metals leader and top-10 risk report author Paul Mitchell said predictability underpinned investor confidence, capital access and strategic agility. “But achieving reliable output is more difficult because of operational complexity – deeper, more complex orebodies, greater variability and declining grades,” he says. “The average grade of copper mined worldwide has fallen by about 40% since 1991. The challenge is heightened by aging assets and capability gaps. Deeper mines require specialist knowledge in geotechnics, logistics and hydrology.”
Speaking at IMARC, Mitchell said: “The mines we operate today in Australia were designed for a 20-year mine life. Many of those mines are now operating at 50-plus years [and] they just weren’t designed for that. The logistics systems don’t work. The installed capital isn’t quite appropriate. The workforce is aging. All these things are impacting productivity ... We remain stuck at productivity levels that just aren't high enough. The answer is absolutely innovation. The answer is technical excellence. We need to do [more] while we continue to focus on decarbonisation.”
Mitchell said it was time for miners to “think boldly about the scope and potential of transformation – reimagining mining from end-to-end”.
“The automotive industry is seen as the shining example of how procurement should be done in its most strategic form”
Companies were already exploring collaboration and partnership arrangements that increased their exposure to midstream and downstream processing and also created pathways to enable them to pool resources, leverage complementary expertise and accelerate project development.
Rashpal Singh Bhatti, group procurement officer at BHP, said industries with complex operational challenges had evolved advanced practices the mining major was working to adopt and refine to “solve problems like we never have before”.
“The automotive industry is seen as the shining example of how procurement should be done in its most strategic form,” said Bhatti, who presides over BHP’s US$25 billion annual global operational and capital procurement spend.
“Toyota is a great example of vertical integration, partnerships and driving better outcomes. The mining industry has never been seen in that [bracket] but that has to change and BHP is determined that the mining industry is about to take on this challenge and be the procurement leaders. We have to move to partnership and ecosystem models. The premise around ecosystem models and partnerships is that we don't have all the answers. We're trying to solve existential problems for the world and we must partner with people, organisations, governments and our indigenous partners in a way that is much closer than we ever have before.”
Australia running out of luck?
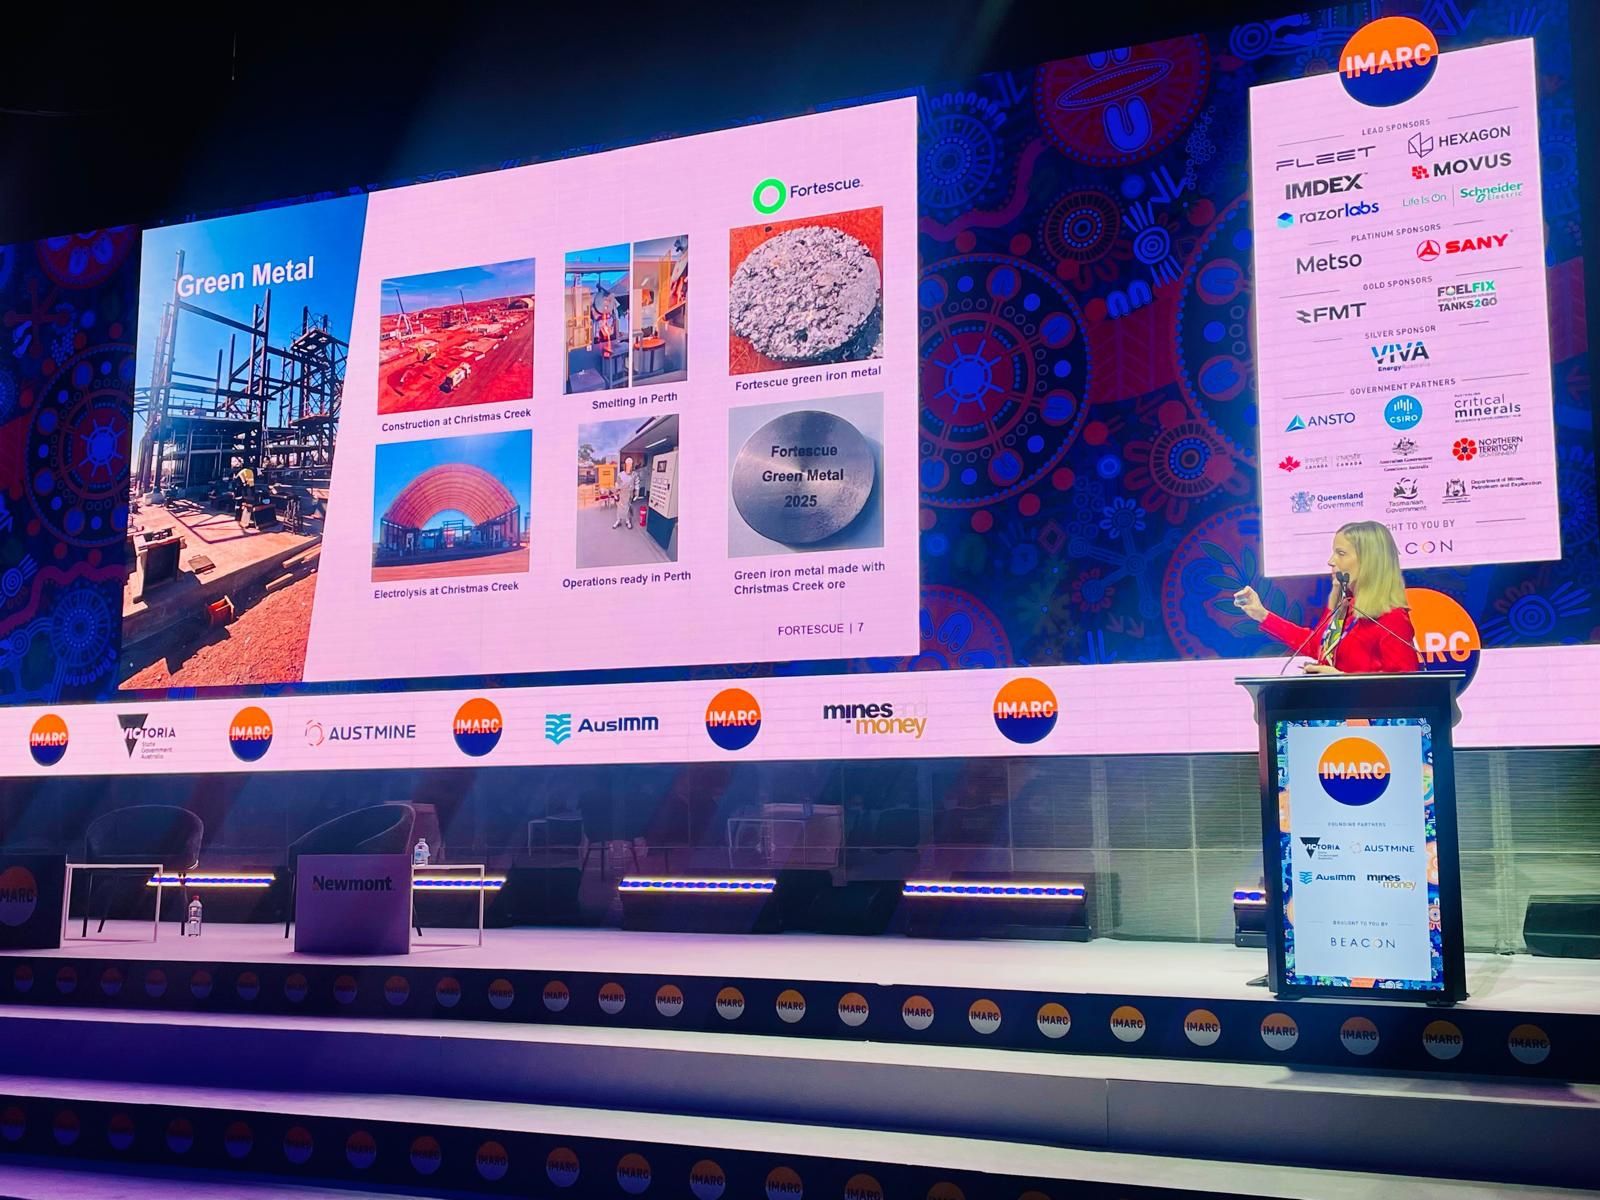
“This presents one of the greatest challenges in our industry and it’s easily the biggest challenge I will tackle in my lifetime,” Fortescue group manager green metal Tijana LaBianca said of the iron ore major’s efforts to bring green iron into the export mix of Western Australia’s Pilbara region, which powered Australia’s circa-$140 billion of iron ore shipments last year.
“The global steel industry is at a crossroads. It accounts for 7% of global CO2 emissions today and production is growing. Yet we know that we need to cut emissions by over 80% by 2040.
“When we’re faced with a challenge of this magnitude it's easy to think of all the reasons why it can't work. But no great industry transformation ever resulted from that type of thinking.
“Australia now stands at a unique intersection of climate responsibility and economic opportunity. The transition to green steel is no longer a distant vision it’s a strategic imperative, and one that can reshape the future of Australian economic prosperity if we act now with conviction and vision.
“Australia’s natural advantages in green iron are undisputed. The hurdles that prevent us from being commercially viable today, which are predominantly high labour costs, technology inefficiencies, long lead times for improvements ... are all challenges which are well within our grasp to solve.
“Fortescue remains resolutely focused on unlocking the economics of green metal in Pilbara to realise our vision of producing 100 million tonnes per annum of green metal, eliminating over 200 million tonnes per annum of CO2 emissions.”
The International Energy Agency says a transformation in the way steel is produced is vital to cutting its 8%-plus contribution to “total energy system” CO2 emissions. China’s blast furnace-basic oxygen furnace (BF-BOF)-dominated steel sector produced more than 53% of the world’s circa-1.88 billion tonnes of steel last year. BOF accounted for plus-70% of global steel output in 2024. Most of the emissions from steelmaking come from ironmaking – turning iron ore into iron – using blast furnaces that burn coal.
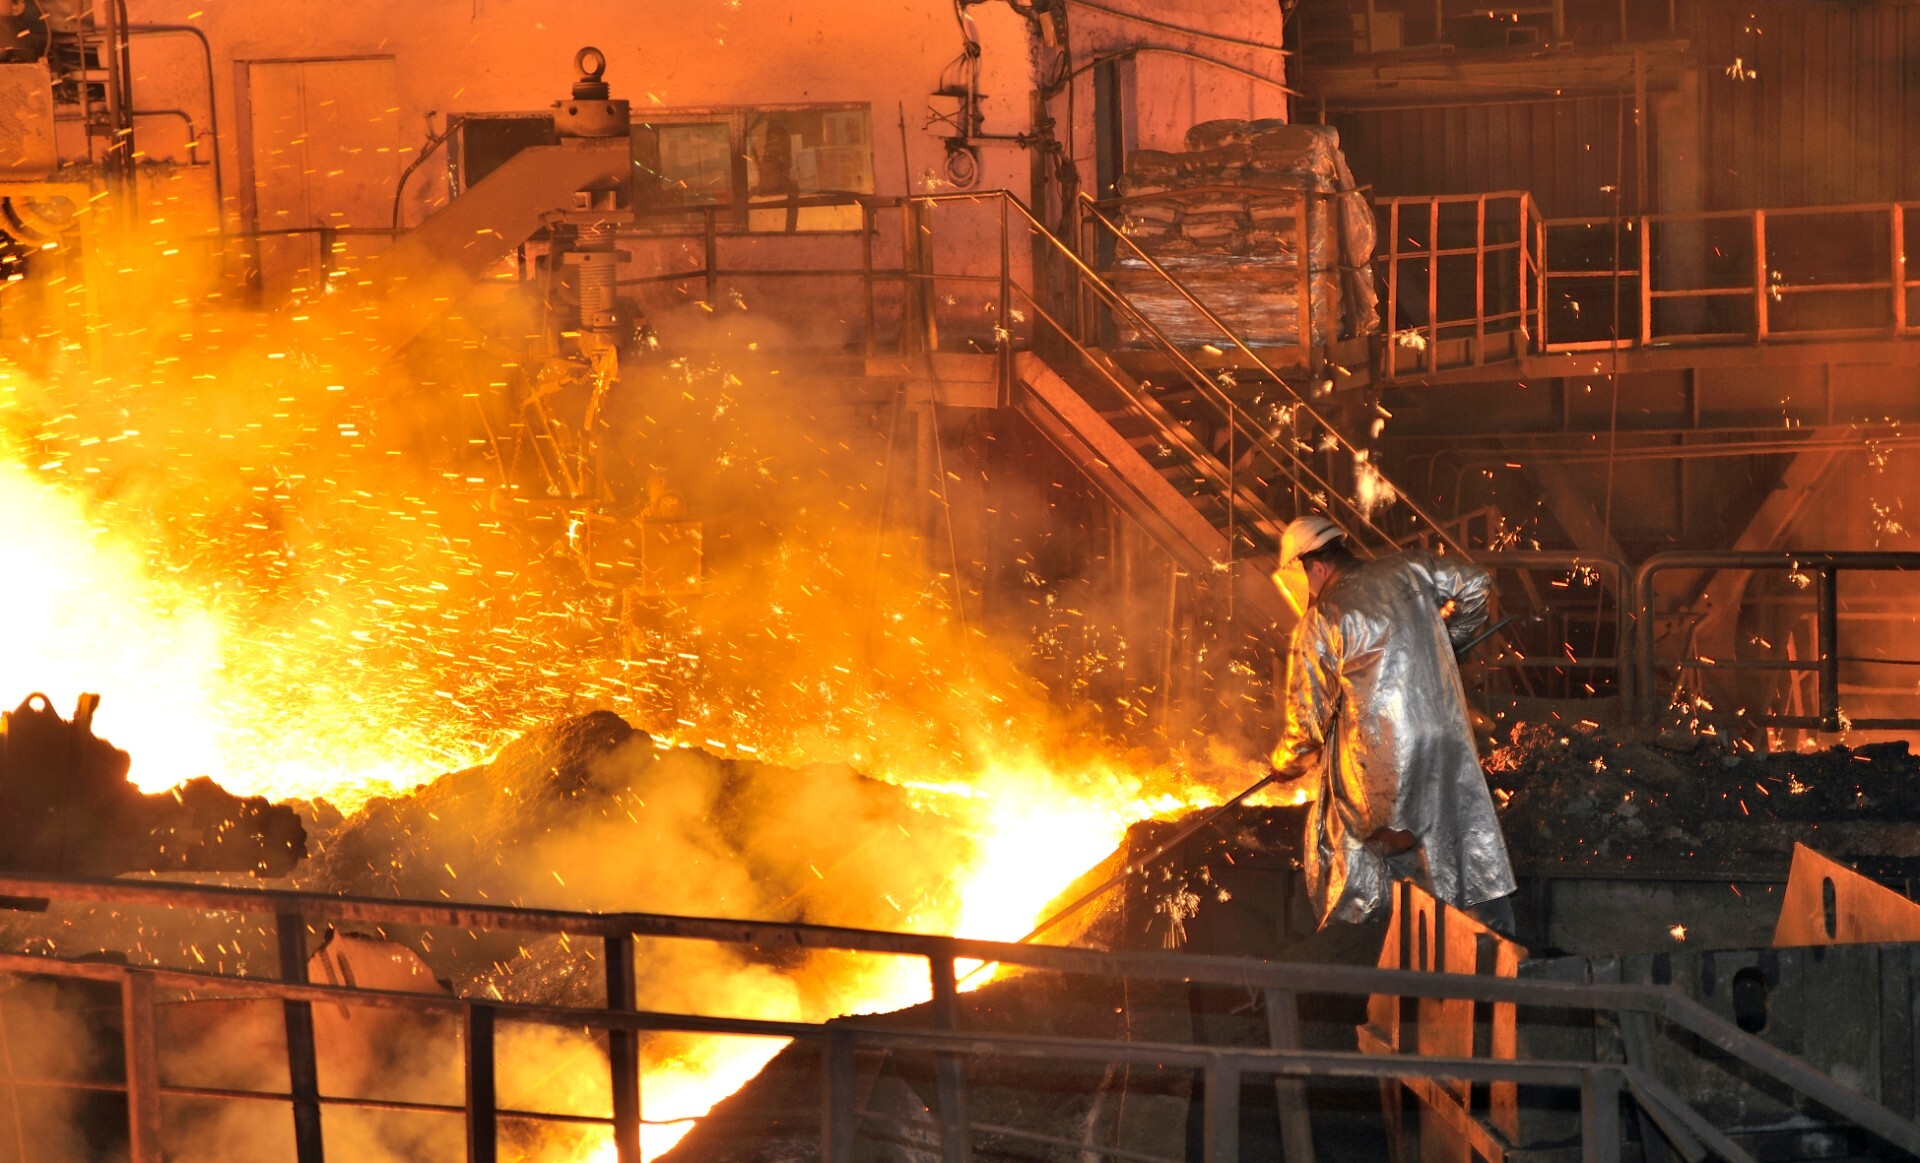
Hydrogen-based direct reduced iron (H-DRI), and perhaps iron ore electrolysis, coupled with electric arc furnace (EAF) steelmaking, could eliminate CO2 emissions depending on the energy source.
Melbourne-based economics, strategy and policy consulting firm Mandala said in a 2024 report WA could produce “at least” 4.5Mt of green iron by 2030 with the right policy and technology settings.
“Over the longer term WA could supply in excess of 14% of global green iron by 2050, leveraging established industrial capability and renewable energy generation potential. This could reduce global emissions by 1.2% [or 456Mt of CO2], nearly equivalent to Australia’s current domestic emissions, generate A$74 billion in economic value in addition to iron ore exports and support 19,600 additional ongoing direct jobs by 2050,” Mandala said. However, it warned, “WA’s future position as a globally competitive green iron producer is not guaranteed”.
Australian Renewable Energy Agency (ARENA) associate director Tanya Hodgson said the country, supplying nearly 40% of global iron ore feedstocks, was “essentially trying to preserve or secure our iron ore exports”.
“But that’s not a sure bet I would say,” she said.
“On the other end of the spectrum we have the green iron opportunity and there’s a range of ambition in that opportunity. But it comes with a fundamental shift in the supply chain, which means that this is a more complicated exercise than it’s maybe being advertised as. And our customers who today buy iron ore, you’re essentially pitching them that you buy iron instead.”
LaBianca agreed. “We see significant product placement risk for Pilbara ores going into the future,” she said. “We’re seeing a [steel] industry preference for higher grade orebodies, with Simandou [in Guinea] and others coming online that present a significant risk for us as a company but also for Australia.
“Why would [China] partner with us to outsource some of what is a critical industry for them today? We think there are two reasons. The first is, it makes a lot of sense for China to accelerate their transition towards green steel. Pollution-related health issues in China cost up to 6.45% of their GDP each year and between 2013 and 2023 they incurred between 800,000 and 1.2 million premature deaths per annum resulting from pollution-related health issues. So there is absolutely a huge imperative in China to reduce particulate emissions, even more than CO2. They’re laser focused on reducing particulate emissions [and] they see the opportunity in a green steel transition.
“And then ultimately it comes down to the energy arbitrage between their best renewables in Inner Mongolia and our best, some of which is in the Pilbara.
“If you assume – and it is a big if – that you can get access to Chinese labour costs, Chinese technology, but use Pilbara solar, you’re producing green iron about $100 a tonne cheaper than China’s best. It is a big if because it means that we have fundamentally reshaped the way that we partner with China.”
Wood Mackenzie steel & raw materials research director David Cachot said China’s steel production had not slowed at the rate many, including WoodMac, were predicting several years ago. While it had peaked it continued to plateau. “Australia has been lucky again,” he said. “Many companies have been again lucky and doing nothing has protected the balance sheet.
“We do see the overall seaborn requirement from China shrinking between now and 2050 by 40%, which means that pretty much Australia will lose half a billion tonnes of iron ore exports.
“Magnetite operations have a role to play in protecting the market share of Australia ... until green iron comes in force. It’s going to be challenging but people are trying. People are putting money where it should be put.”
Dane Noble, Australia New Zealand industrial decarbonisation lead at engineering major AECOM, said government had a crucial role to play in stimulating investment in technologies and infrastructure through incentives and mandates. “If we just apply too much carrot then what ends up happening is we end up subsidising industries or facilities that otherwise wouldn’t be economic and that’s just not sustainable for the long term,” he said.
“On the flip side, on the stick side of things, we need our facilities and our industries to be competitive, both globally and domestically. If there’s too much stick they’re just not able to compete on an unlevel playing field with foreign importers who don't have the same level of regulation.”
Beyond the critical iron ore space, Australia has almost uniquely in a global context established export strongholds in commodity areas in which China otherwise dominates supply chains. They include rare earths, lithium, graphite and titanium minerals.
Outside of the bulk commodity areas – including iron ore, coal, bauxite and in some cases copper and gold – Australia faces increasing cost trials. “The big challenge we see here in Australia is actually cost competitiveness,” said National Reconstruction Fund director, Lauren McGregor.
“We cannot build the end-to-end value chain here so we need to do that with partners and we need to find a way to collaborate with allied nations.”
Nero Resource Fund founder Russell Delroy said from an investability standpoint cost curves were always fashionable.
“Two years ago we could have sat here and talked about a pretty robust nickel industry in Australia. It is now completely eviscerated and in my mind never coming back,” he said.
“That is because it is fundamentally uncompetitive. And that is coming for us beyond nickel.
“We have really serious self-reflection required to work out how we stay cost competitive in the global landscape.”
ESG continues to shape a new tomorrow
With governments trumpeting mineral security alliances and astronomical compensation claims related to a Brazil mine tailings dam disaster producing international headlines at the same time, it’s hard to argue with IGO chair Michael Nossal’s view that mining’s public profile – good and bad – has never been more elevated. “I’ve been 35 or 40 years in this business and we sailed under the radar for a very long time. We’re no longer under the radar,” he said at IMARC.
It was therefore inevitable that the very public debate about whether mining has moved past “peak ESG” or is really just getting warmed up would be woven through IMARC discourse.
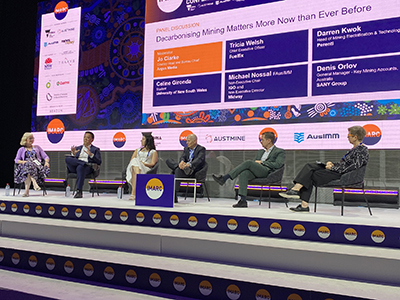
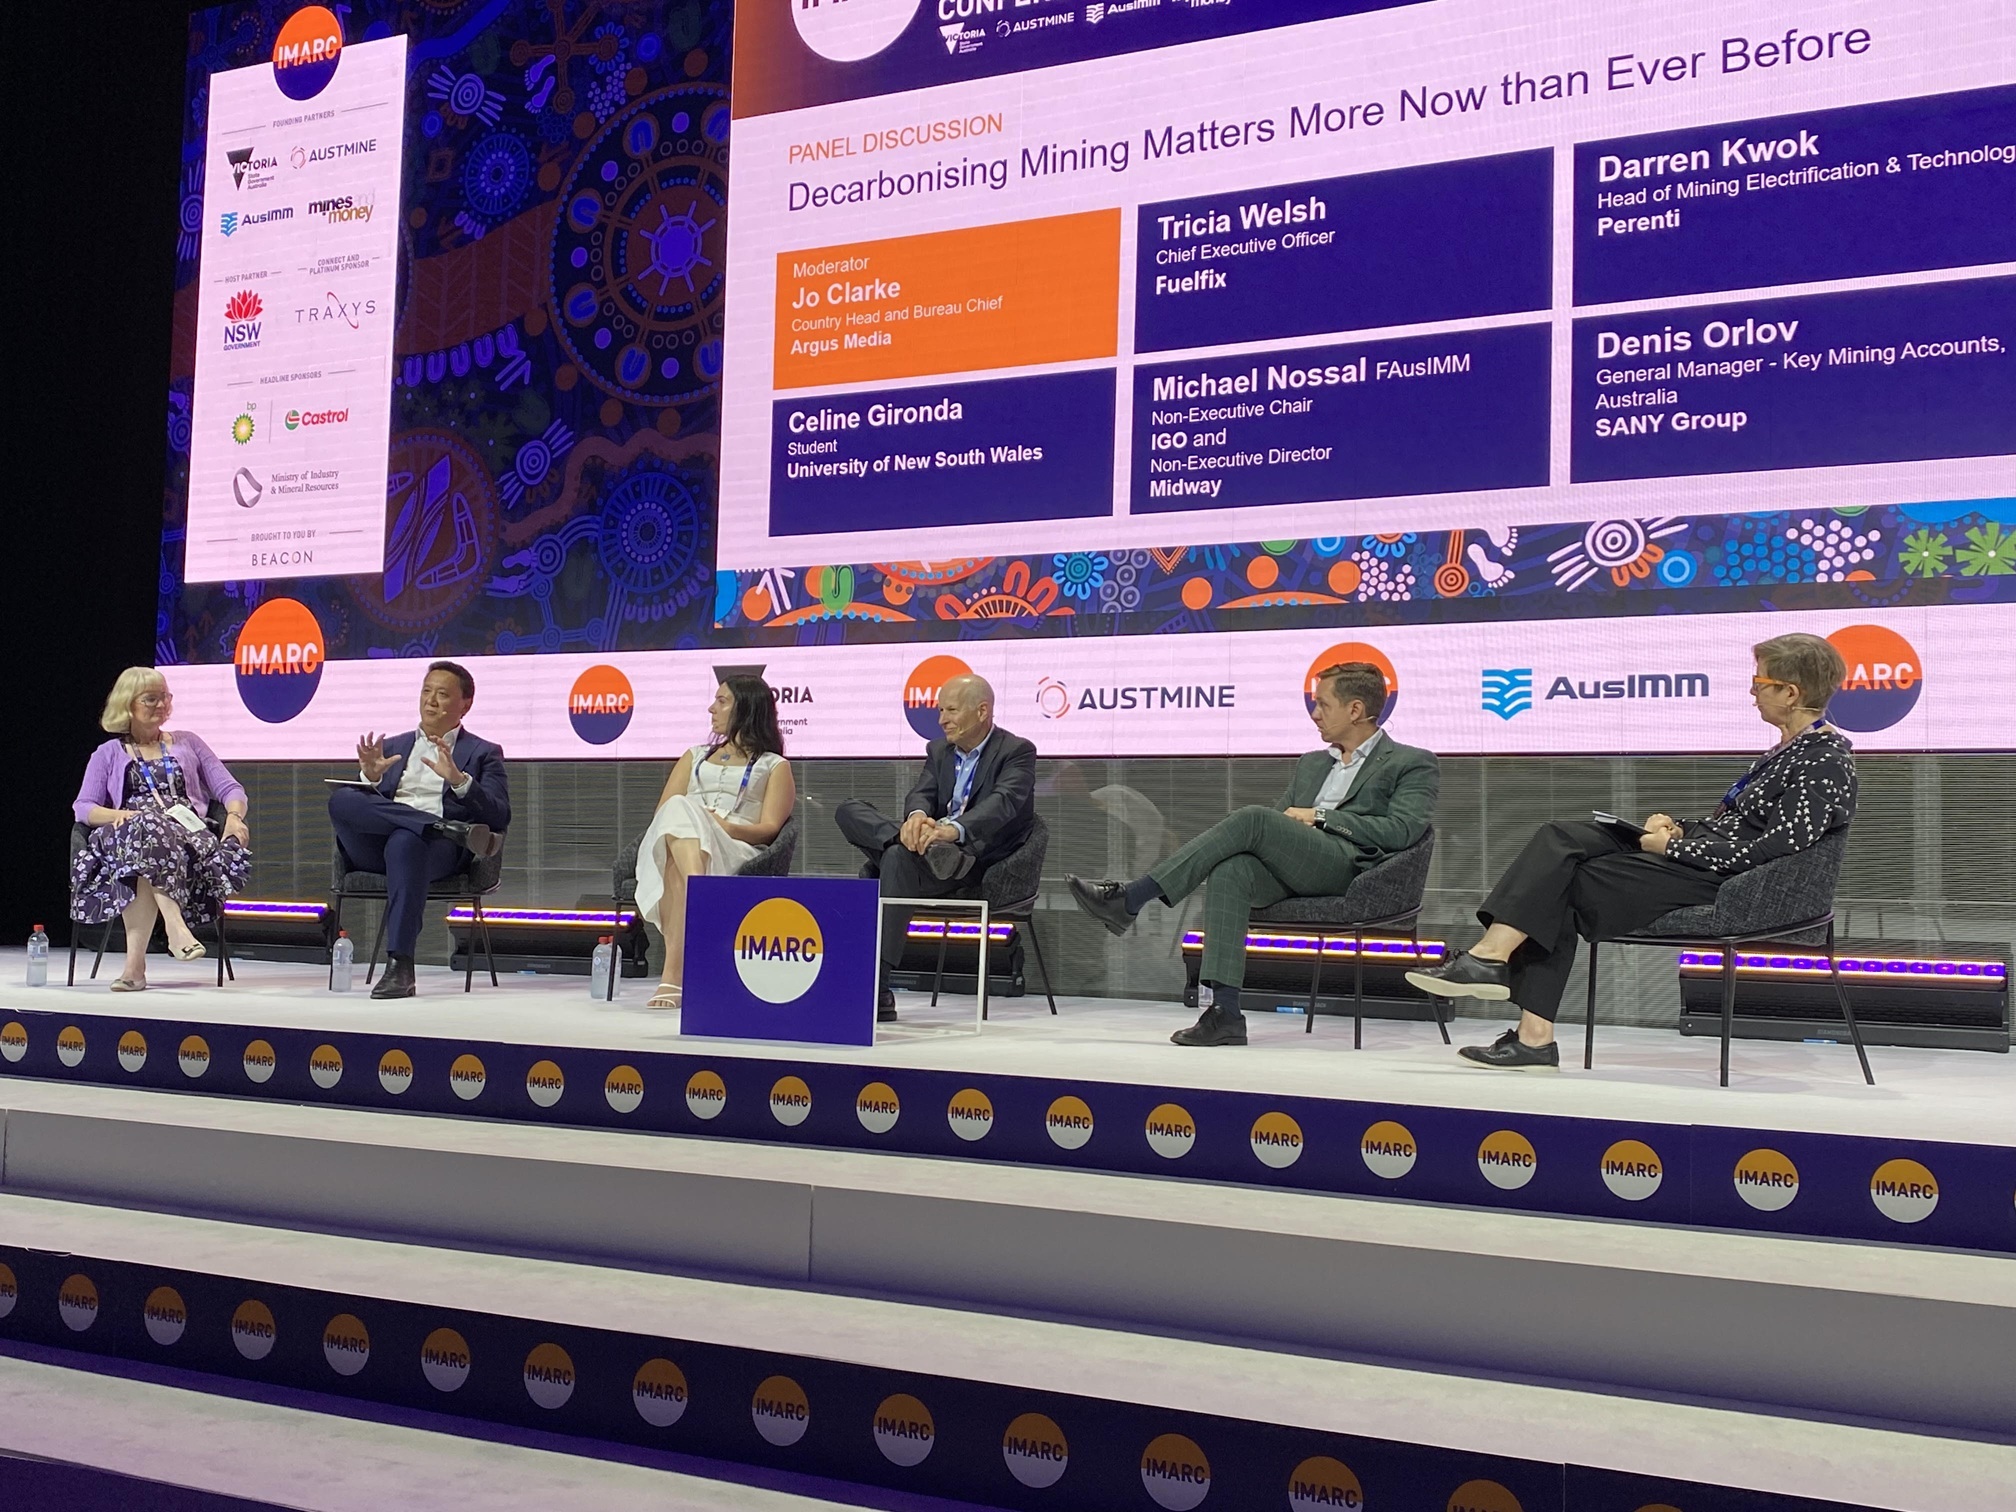
“I don’t think you would have even come up with this topic three or four years ago,” Nossal said of a panel discussion about why decarbonising mines mattered “more now than ever before”. That signalled a change in the tone of the debate, but not the underlying currents.
“The general term I’ve heard from IGO investors is ESG fatigue,” Nossal said.
“There was a very big investor push; everyone wanted to invest in an ethical fund and invest in companies that were actively showing their progress on decarbonisation. That has waned in the last little while.
“We've got some people doing really good things and others who are taking advantage, to be perfectly honest, of this hiatus, to basically park a lot of their projects and say, we’re not going to invest in that right now. We'll wait until we have to.
“I think the industry has to keep going and think big and stop deferring things that are going to come anyway. In the longer term it’s going to be really important that we keep going in order to maintain that social license.”
Economics and pragmatism might dictate the pace of decarbonisation in mining and wider industry, but transparency and the seemingly inexorable rise of higher intelligence really have become material counterweights in engagements between industries, community groups, governments and the financial sector on social and operating license.
The impact of operating licence terms on mining economics is only becoming more profound and is not something that is likely to wane in future.
“Those who ignore ESG and those who ignore license to operate just aren't going to be able to raise the capital needed, aren’t going to be able to attract the workforce and aren’t going to be responsible to continue what our industry needs to do,” said EY’s Paul Mitchell.
“One failure for the industry impacts us all and I think we all need to remember that as we go forward.”
“We are ultimately going to live in a world of traceability,” said investment manager at the Australian Renewable Energy Agency (ARENA), Anish Muchhala. ARENA is an Australian Government-backed body with cA$14 billion of public funding capacity to put behind industrial decarbonisation technologies and projects.
“We love to know where our produce comes from and where our meat comes from. I think we’re moving towards a world where we want to know what’s going into our iPhones and where our nickel and lithium is processed. We’re seeing, particularly out of Japan and Korea, more interest from the ultimate customer in the [decarbonisation] technology side than I've ever seen before.”
Joshua Lane, a senior technology advisor with Rio Tinto’s Australian aluminium business who attended IMARC, said he thought decarbonisation and ESG discussions at this year’s event “matured”.
“The [ESG] label may be under pressure, but the fundamentals remain. Environmental care, social responsibility and governance integrity still define resilient businesses. What is changing is how we embed them.
“Less talk, more integration. Sustainability only works when it drives performance. Not as a box-tick exercise but as a capability that builds efficiency, attracts investment and earns trust.”
Lane, who has spent more than 20 years in the mining and resources technology space, said a standout message from IMARC for him was that mining’s “transformation” was accelerating.
“Those ready to balance energy, technology and innovation will define what comes next,” he said. Harmonising energy demand and decarbonisation was key. “Mining cannot afford to prioritise one over the other. Operational efficiency and financial viability depend on treating them as a single system, optimising both, not trading one off.”
According to Darren Kwok, head of mining electrification and technology at one of the world’s largest mining equipment fleet owners, Australian mining and drilling contractor Perenti, much progress is still being made as the industry transitions through hybrid, diesel-electric and other new machines that are “stepping stones” to a generation of fully electric and battery-powered units. Empirical knowledge was being accumulated. Workforces were being trained and grown. Regulations were evolving.
“There’s certainly a lot of paddling going on under the surface,” Kwok said.
“If you look at what we're trying to push forward with, as stepping stones, we’re now talking about diesel electric and we’re now talking about hybrids, where you no longer have the fear of having not enough power to drive through a single cycle. You can have a shift worth of flexibility.
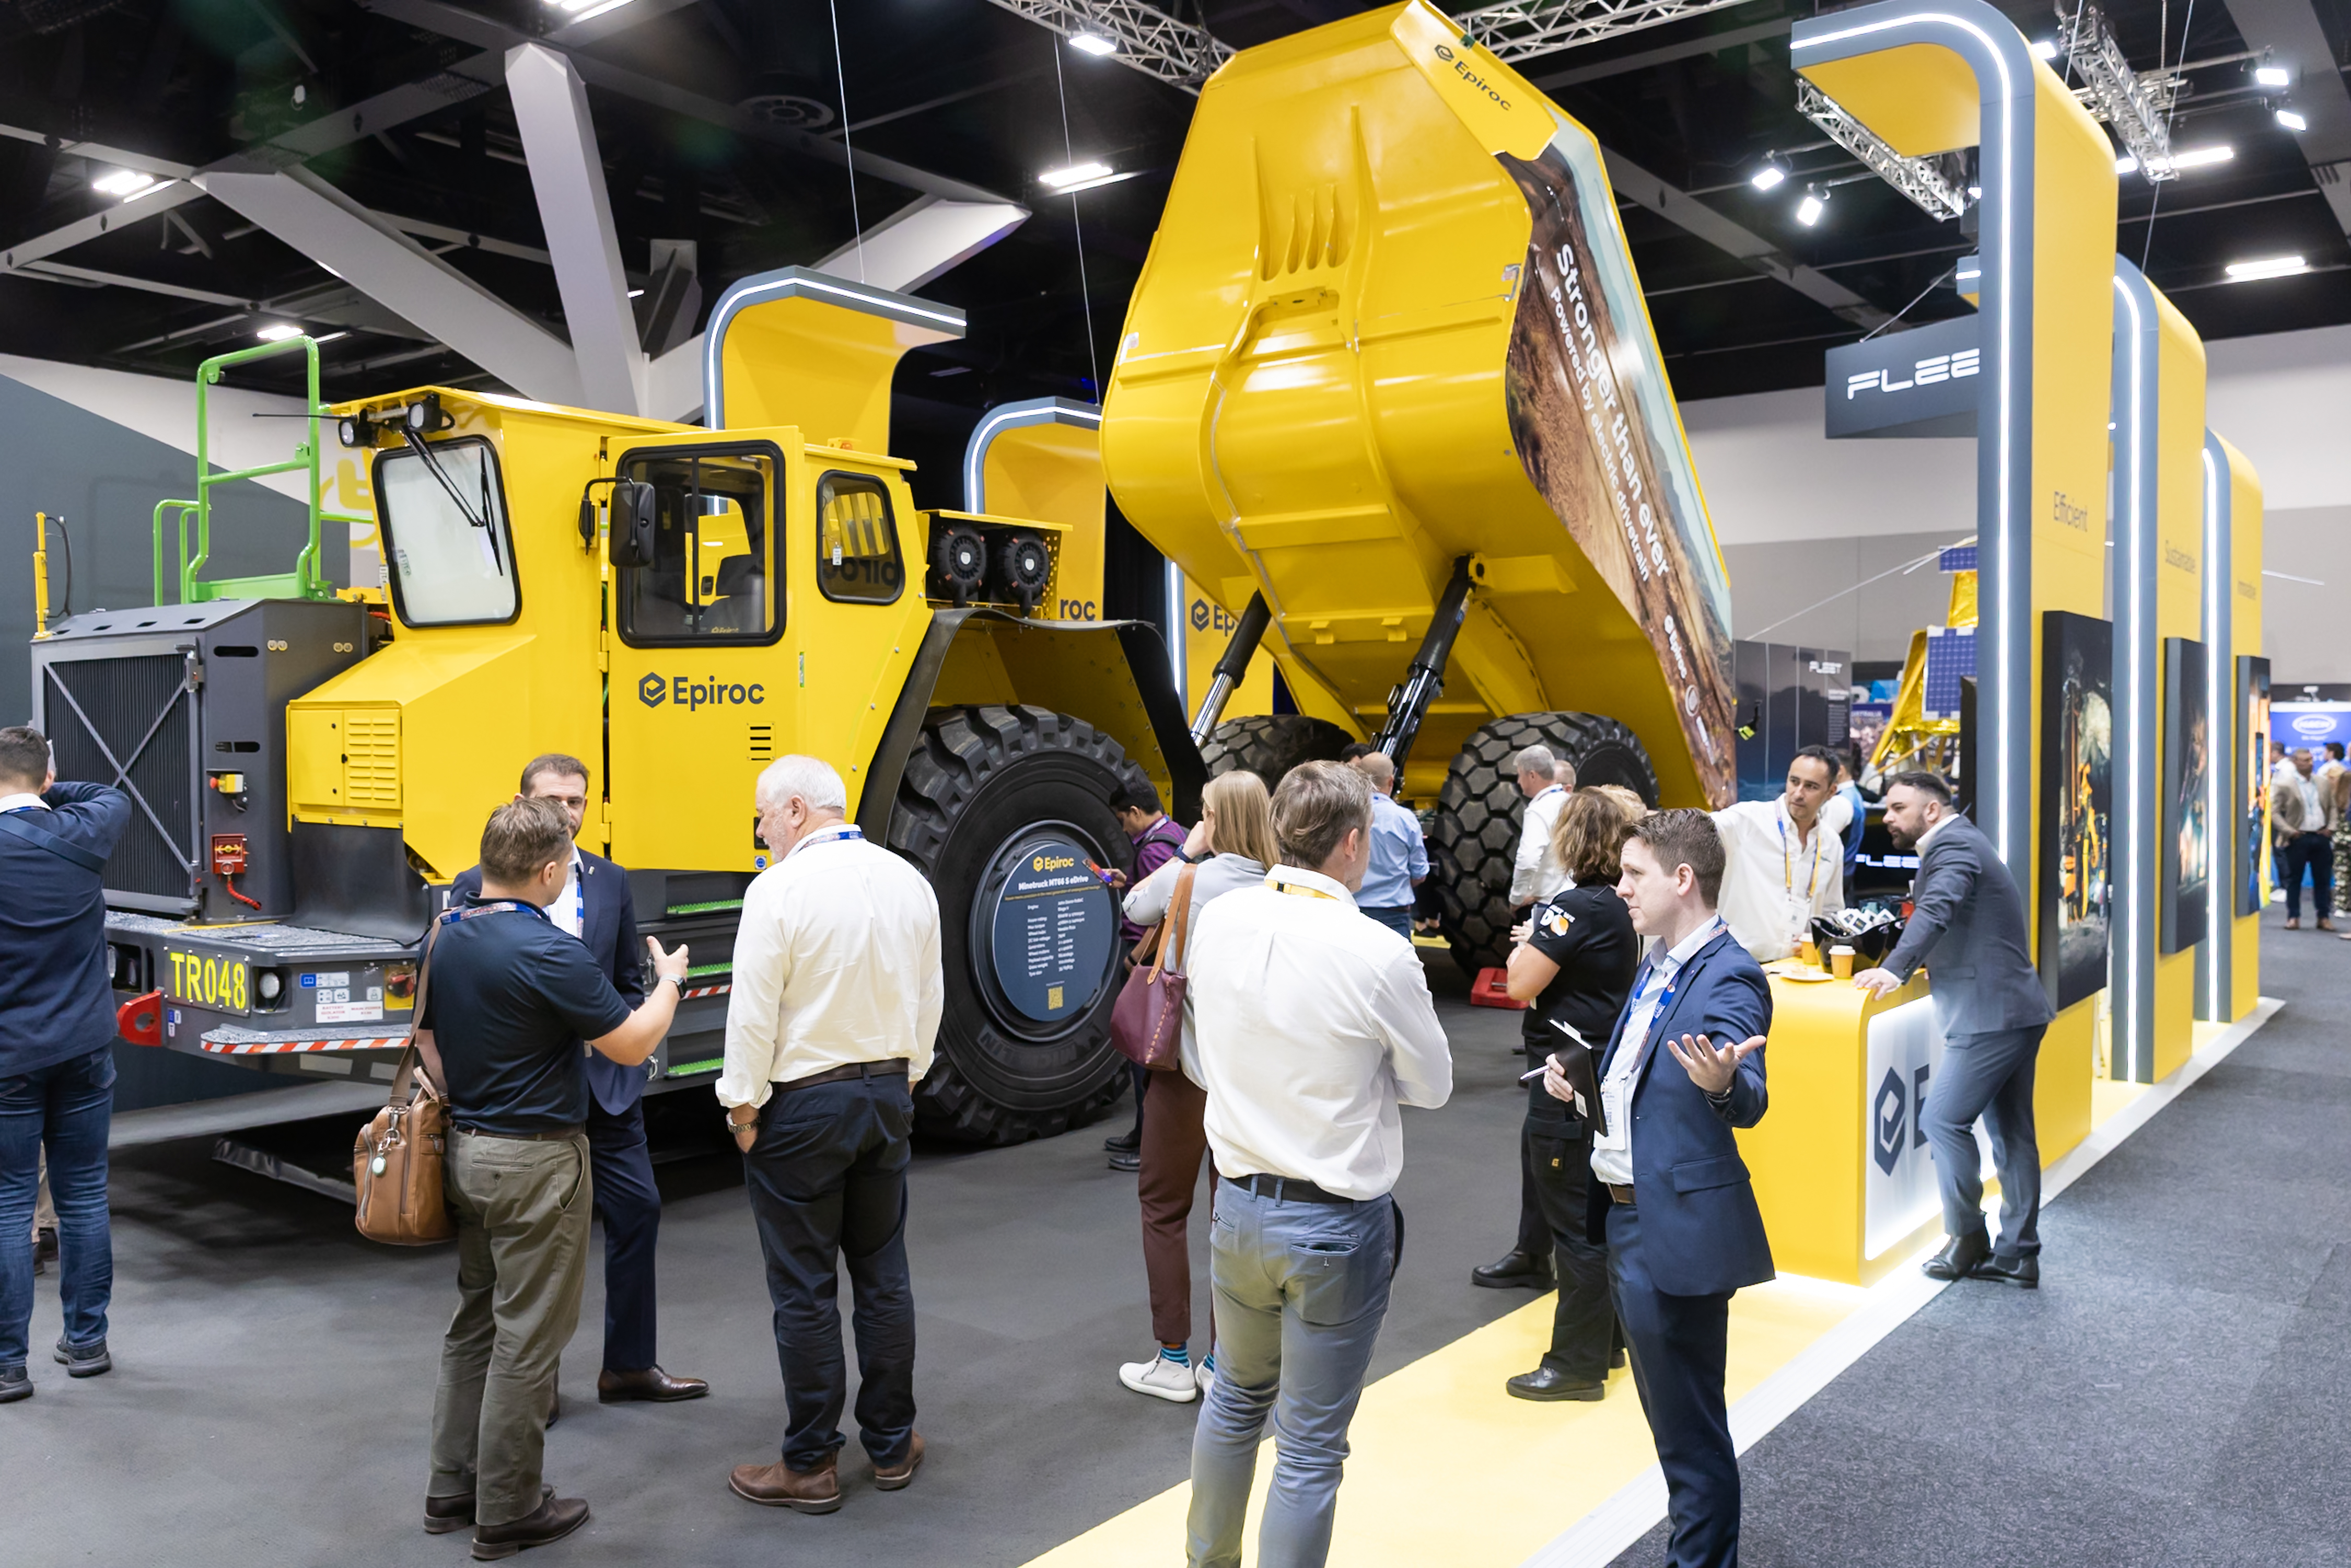
“You can reduce your emissions by 15-to-20% but more importantly your workforce will understand what an electric drivetrain looks like. They’ll understand the benefits of an electric drivetrain through speed, acceleration and breakout force increases.
“I think we’ve also over-rotated on the emissions aspect of these machines. Yes, it’s very important. We want to reduce our emissions. However, what we’ve missed is that these machines, at a technical level at least, are just simply better machines.
“They have fewer moving parts, they generate less heat, they go faster and they break out more dirt. In my experience in this industry we like the newest and brightest toys. We've never said no to them ever. So these are series one machines. They’ll have their quirks, they won't be as reliable, but that is no different to any better machine that’s come before.
“The fact that it’s electric or diesel electric or hybrid shouldn't scare us away from the change. We will find the operational benefits. We will find the return on investment. We will make the machine better and then it will stop becoming an electric machine and just be the machine.”
In terms of the broader decarbonisation question, Kwok said in his view it was “not if, it’s when”.
“It’s a conversation about time,” he said.
“Again, looking at it from a technical standpoint, we’re [miners] involved at a perfect moment in time.
“The automotive industry has already experimented with electrification. The technology is getting better by the day and the scale now in batteries is enormous. We understand the value chain very, very well.
“We get to start the conversation in mining in a far more mature state than infancy and I think that brings us into a really interesting place to be able to execute as opposed to trying to design, build and develop at the same time.”
A fundamental driver of a shift to safer, better equipment and significantly better operating conditions is the workforce of today – and tomorrow.
Celine Gironda, a mining engineering student and cadet, wants to see the industry accelerate its decarbonisation journey through investment that balances current needs with future imperatives.
“This is going to be my problem that I’m inheriting as I enter the industry,” she said.
“It’s hard to equate the negative perception my generation has towards mining with the things that we’re trying to achieve in the future. As I say, it will be my problem.
“It isn’t that moment, but it will be.
“Our mines are only as successful as the communities they connect with.
“Without a social license to operate there’s not much I am going to be able to do.”


