

IMARC 2025: 10 vital conversations (Part 2)
- 10 December 2025

A well-timed US-Australia minerals deal, gold and silver price volatility, and slowing world economic growth were in the headlines during this year’s International Mining and Resources Conference + Expo (IMARC) in Sydney, Australia. Digging a little deeper, though, there were at least 10 major themes to come out of the 2025 edition of one of the world’s major annual mining investment, trade and technology forums.
-
China, not surprisingly, figured in many event conversations. A common question asked was, how does the West, in particular, “catch up”, or restore its leadership, across vital supply chains? It seems to presume China will stand still, which IMARC audiences heard was unlikely.
-
The US is absorbing a lot of the world’s attention – for a variety of reasons. But another part of the world remains its primary growth engine and it’s hard to see what could change that.
-
EY’s list of top 10 mining risks for 2026 has operational complexity as No.1. IMARC probed operational complexity from all angles and, ironically, some simple solutions resonated most.
-
Australia has been labelled, rightly or wrongly, the lucky country. With its prosperity this century underwritten by iron ore, coal, LNG and other commodity exports, it now finds itself at a crossroads. Concerns, lots of them, were raised about the country’s ability to come together on a path to continued prosperity.
-
Strong post-COVID ESG “signalling” by corporates (and governments) has been somewhat muted by Trump 2.0 and other factors. But the mining industry, broadly, knows it must be better or it will continue to struggle to regenerate project pipelines and build new mines at sustainable capital intensity levels. IMARC dived deeply into where and why this improvement must occur.
-
For a few years now “smart mining” has referred to the digital and automation undercurrents starting to shift the industry’s operational focus. However, as IMARC 2025 amply demonstrated, it is becoming a much broader and more urgent discussion than it was when the term was coined.
-
Public-private partnerships are key to rapidly reshaping new ex-China mineral-based value chains. That ball is rolling in countries such as Saudi Arabia and also now in the US, Australia and Europe. Where and how it lands will be watched very closely up to IMARC 2026.
-
The industry is spending more freely on digital and sensing technologies and a large number of start-ups are pouring into the space. The big dollars being paid for acquisitions show where the “smart money” is going. But is the industry investing enough in innovation and technology and is it another area where China is simply moving faster?
-
“People are our most important asset/resource” is a favourite mantra of company marketing departments. In mining, kneejerk responses to predictable (and predicted) commodity price cycles and the ongoing hollowing out of Western mining academia jar somewhat with the rhetoric.
-
“Critical minerals” are taking all the headlines but while gold seems to be one of the few metals left off lengthening country critical mineral lists it continues to dominate exploration budgets and get most investor attention. This is not a cyclical phenomenon, it’s an evergreen trend. When mining, broadly, is supposed to be capital, people and generally resource-constrained, what does that mean?
‘Smart mining’ has new meaning
There are added dimensions to the technology-centric “smart mining” mantra of several years ago.
Mining still needs to get its house in order vis-à-vis productivity, safety, asset utilisation, waste generation and management, capital and energy intensity, and procurement. Technology will be key on all fronts.
But it won’t necessarily be enough to accelerate project delivery, increase the sustainability of new mines, bring new skills into the industry, or excite new investors. The industry needs smarter funding mechanisms, regulations, supply chain alliances, and recruitment and training methods. It generally needs to be a lot smarter about the way it works with governments, NGOs, traditional landowners and communities.
And it must work more constructively with governments to clear deep permitting backlogs.
Former UK deputy prime minister Dominic Raab, now head of global affairs at Appian Capital Advisory, said “smarter regulation” was crucial to efforts to boost mining investment and deliver the secure metals supply chains IMARC 2025 heard so much about.
“It cannot be beyond the wit of regulators across Canada, US, Australia and the EU to come up with a better permitting system which creates greater certainty for investments, clearer criteria and more predictability,” he said.
The event heard collaboration and partnerships were building, though “to really drive the outcomes that are impactful we need to move from talking about it to actually doing it in a focused way”, said Schneider Electric ANZ/Pacific mining, minerals and metals regional segment leader, Emilie Ditton.
Interestingly, EY’s global mining and metals leader Paul Mitchell said the industry was seeing district-scale partnerships and collaboration opportunities, with real synergies and other economic and socio-economic benefits, driving investment in mining, including M&A. This was seeing infrastructure-sharing change the economics of new developments in Chile’s copper sector, as an example, while South Australia’s BHP-dominated copper space would see major long-term benefits from new public-private partnerships.
“I think for too long iron ore and coal in Australia were very much barriers to collaboration,” Mitchell said.
Rowena Smith, CEO of New South Wales rare earths miner Australian Strategic Materials, said: “I find it really interesting that I have been in this role for four years and I’ve been talking about the importance of partnering since the day that I started.
“I’ve been talking about the fact that the only way that we're going to rapidly get this end-to-end supply chain up is by people focusing on one point in that supply chain, developing deep expertise, and then partnering with others so that all parts of that supply chain are getting up at the same time.
“We’ve got to think about it across jurisdictional boundaries. And largely the industry has been extremely resistant to it until about six months ago.

“What has triggered the shift? The US announced the landmark MP Materials deal where they put in government equity; they said, we’ll do offtake with a price floor. And then they said, we will do it for others.
“And companies have realised they can’t get there with their, I’m-going-to-do-everything model that they’ve been using, but could get there if they partner. And so there’s just a frenzy of activity going on at the moment where everybody’s talking about what’s possible and how they could work together.
“So I think policy doesn’t have to be about choosing winners and giving money. You can create opportunities that then motivate people to work in a different way.
“The Western Australian iron ore industry is a classic example where policy didn’t require or motivate people to work together. It actually motivated the opposite. And we’ve got gross inefficiency of capital. And that’s an industry that historically could afford to be that inefficient.
“But as we go forward none of our industries can afford to be that inefficient.
“We have to be cleverer.”
Amid plenty of talk about fast-tracking new primary and secondary sources of minerals and about feeding critical materials into domestic and rebuilt international industrial value chains, European Raw Materials Alliance (ERMA) director Massimo Gasparon said mineral processing and refining required new strategic thinking.
“Contrary to common opinion Europe does have some significant mineral deposits,” he said.
“But the real weakness is in the processing and refining. And this is a tragic event in a way because we use to have the leadership in some of the refining and processing in the past. The techniques for separating rare earths on a commercial scale were actually developed in France back in the 50s and 60s. But all that expertise has been lost over time.
“When you look at the most important papers that are being published on mining and mineral processing these are all coming from non-European, non-Western world countries and all the innovation that is being developed now will be the new mining and mineral processing techniques of the future.
“We need to become more competitive when it comes to innovation. We need to become more competitive when it comes to producing the right skills in the right numbers to sustain the growth of the minerals industry.
“International partnership can help in all [areas], of course, by providing an opportunity to swap notes, to share knowledge and to understand what the rest of the world is doing.”
Paul House, CEO of leading Australian mining technology company, IMDEX, said in a keynote IMARC 2025 address mining’s future depended on moving knowledge and not just rock.
“Our industry is under pressure. Operating costs are rising ... yet productivity gains are harder to unlock. Meanwhile, demand for critical minerals is accelerating,” he said.
“How do we deliver more – faster, more efficiently and with greater impact – without compromising margins or sustainability?
“We [IMDEX] think about this challenge as a systems problem not just an operational one.
“Productivity isn’t only tonnes per shift; it’s the flow of trusted information that connects geoscience, engineering and management.
“If we can shorten the distance between measurement and decision, we change the economics of mining itself.”
House said long-term connections with more than 500 resource companies and over 150 drilling contractors gave IMDEX clear insights into mining’s significant trends. “Our people on the ground talk daily with customers and stakeholders and the same themes emerge everywhere: labour shortages in key regions, escalating input costs and orebodies that are deeper, more complex and harder to access,” he said. “The traditional response – more drilling, more equipment – no longer delivers the returns it once did.
“What’s needed now is a shift from volume-based productivity to intelligence-based productivity.
“Better early information widens your future choices. Poor or late data narrows them. The companies that learn to treat data this way will redefine what productivity really means.
“The future of mining isn’t about doing more it’s about doing it smarter.”
Public-private partnerships
“The Chinese have supported their industrial champions for years, so this is not something that the winners haven’t been doing,” Mark Kristoff, CEO of US$10 billion-a-year commodity trader Traxys, told IMARC 2025 when asked about expansion of public-private partnerships by Western governments and miners. Pre-event news of a new multi-billion-dollar US-Australia critical minerals framework, unlocking public funding for Australian projects, followed the “transformational public-private partnership” announced in July between California rare earths miner MP Materials Corp and the US government under which the government committed significant equity funding and a long-term floor price for RE magnet material supply.
MP subsequently signed a new supply deal with Apple.
“This is something we need to do selectively for it to be successful,” said Kristoff.
“We need a competitive cost of capital if we want to compete with the lowest cost of capital around the world, which has been China historically; the Japanese and the Koreans, to an extent, have also done it. The West has failed miserably in providing capital for extractive industries, or perhaps transformational industries, and we have to fix that.
“The industries that we bring to bear have to be collectively profitable and in the lower quartile of the production cost curve, if possible. So they have to make sense. You need smart people thinking about the projects. But then you do need the government support.
“There finally is an awareness and a recognition that we need to create partnerships along shared value chains.
“Saudi Arabia is a perfect example. Long-term competitive capital availability, loan guarantees, supported by the government, a supportive fiscal environment for permitting, land allocation, local workforce training and development, and good fiscal oversight for corporate stewardship ... If you bring all these pieces of the puzzle together with long-term cheap energy availability, you're going to attract a lot of industry.”
Traxys has signed a five-year offtake agreement with Australian RE developer, Arafura Rare Earths, owner of the proposed US$1.2 billion Nolans project in the Northern Territory. Nolans was one of two initial “priority projects” named to receive support under the new US-Australia framework.
“There's obviously benefits for Arafura and the Nolans project,” said Arafura chief financial officer Peter Sherrington.
“But I think it’s probably much broader than that. There are sector-wide benefits as well.
“The interest from the US government and EFA [Export Finance Australia] around equity opportunities is demonstrating how serious the West is taking the issue of rare earth supply and building out those value chains. Having resilient value chains is critical to underwriting industry and manufacturing.
“It’s good for our industry counterparts in the space. I think the big thing it does is it de-risks raising money for what are really quite challenging projects from an equity perspective. They’re very capital intensive.”
ASX-listed Syrah Resources has a world-class graphite resource and mine in Mozambique and has received US government loans and tax credits to build a downstream active anode material plant in Louisiana, USA. CEO Shaun Verner said at IMARC 2025 deeper government involvement in public-company owned mines and midstream processing was “a necessary evil if we’re going to have any ex-China capacity built”.
“In our case we secured over four years two US government loans in the support of building downstream capacity in the US and supporting the upstream mining operation in Mozambique,” he said.
“The reality is that it was extraordinarily hard and long to get those in place and even once they’re in place the markets are not mature yet, pricing is opaque, demand shifts and most of the institutions are not built to deal with that type of volatility.
“So this does need to happen if we're going to get alternative sources of supply, but it all goes back to the question of ... is there an end market that is demanding this material and demanding that it doesn’t come from China? The government support is pretty critical on the supply side but that question has to be answered at the same time.
“We’ve got the largest resource in the natural graphite industry and that’s the reason it got developed. It is the best resource. And at the scale that it can operate it should be in the first quartile of the cost curve. The issue is that demand hasn’t caught up in the ex-China world and that’s because customers want a co-located source of supply. They want it to be accredited to Western standards. They want it to be uncontracted if they can get it, so available when they want it, not necessarily on a long-term contract, and they want it at a China price.
“And these things are just fundamentally inconsistent.
“If customers don’t cure their addiction to lowest possible cost supply from China there will be no inducement for projects anywhere else because ultimately they’re the ones who make the purchase decisions.
“The other fundamental is that we will never be able to compete on capital cost [without the public funding mechanism]. We might get there on opex but building a facility in the US, as we've done, or in Australia, we just can’t compete with Chinese capital costs.”
Technology and innovation
Mining machinery heavyweight Caterpillar’s recent circa-A$1.1 billion acquisition of Australian mining software vendor Micromine continues a now-five-year-plus trend of M&A and financing that has seen more than $22 billion flow into the nascent mining and metals tech space.
Traditional equipment majors such as Caterpillar, Komatsu, Sandvik, Epiroc, Hitachi Construction Machinery and Weir have joined software companies such as Hexagon, Bentley Systems and Constellation Software, and outside investors led by private equity groups, in buying up smaller technology firms. They all see technology adoption picking up, finally, in mining. The original equipment manufacturers (OEMs) see technology and related aftermarket services making material contributions to their businesses over the next decade.
Start-ups and scale-ups focused on exploration, mining, processing and metal recycling technologies have now raised billions in financing in a watershed five-year period unlike any other in centuries of mining.
“IMARC 2025 reinforced that mining’s future is not just about extraction it is about transformation,” said Rio Tinto’s Joshua Lane, a senior technology advisor with the group’s Australian aluminium business.
“Global momentum is building. During IMARC, the United States and Australia announced a new Framework Agreement on Critical Minerals and Rare Earths, strengthening cooperation, securing supply chains and signalling a shared commitment to responsible growth. For mining and technology leaders, this alignment matters. It is a reminder that policy, investment and innovation must move together to build resilience and competitiveness.
“From digital integration to data driven decision making, technology is no longer an enabler, it is the foundation. Those who understand this will lead the next phase of operational transformation.”
EY’s Paul Mitchell says digital transformation is gaining pace across the sector “as companies seek better solutions to enhance cost management, productivity, safety and sustainability in a more complicated environment”. The firm’s 2026 mining risks and opportunities survey suggested about one-fifth of industry respondents would significantly increase spending over the next 12 months to build AI capabilities.
“Agentic AI also offers huge potential to augment human capabilities and create greater value across the business,” EY says. “But making the most of solutions depends on identifying opportunities to drive tangible business impact and updating risk management processes. So far, ROI in AI and other digital initiatives has been limited, hindered by siloed data and misalignment with business needs.
“Gains have been realised within core operations, but more value will come from an end-to-end approach that leverages a unified data and AI backbone.”
Paul Canterbury, DXC Technology’s head of digital evolution in mining, hosted an IMARC 2025 panel discussion on the industry’s digital evolution and spoke about high-value technology and data integration in the industry.
“I think the biggest shift we’re seeing in mining’s digital transformation is the integration of data,” he said.
“Typically data is in silos a lot of the time. Now there are suddenly new standards where AI can liberate data from organisations and AIs can talk to each other to get work done. The surfacing of data in organisations and the ability to take action in real time as a consequence of that, all driven by AI, is going to be a game changer for digital transformation.
“Coupled with the current acceleration in the adoption of AI there are significant productivity benefits that can flow from the adoption of digital twins and spatial computing.
“I do think this enhanced immersive digital technology is one of the things that’s going to amplify that again. It is providing us with a way to work more collaboratively with site operations and maintenance personnel, where someone can be with you virtually on a site doing work, to achieve better, safer and faster outcomes.
“The industry literally has mountains to move to extract the minerals the world needs for the energy transition.
“The world needs the industry to move faster.”
Mark Frayman, managing partner at Orion Industrial Ventures, said at IMARC: “I think we're just beginning the broader critical mineral super cycle. It’s at the forefront of all geopolitical discussions globally. We'll see technology and technology access, much like it is in semiconductors, become really strategic and the leading startups will get government funding. We’ll start to see really large influxes of capital come into the sector. I think it's a great time to be a start-up founder [and] an early-stage venture investor.”
People are mining’s bedrock resource
A report released by IMARC 2025 sponsor Bain & Company ahead of the event underlined mining’s oft-repeated claim that people drive operational change and real value in the industry. Breakthrough technologies such as automation and generative AI “present exciting opportunities for the sector and have understandably become a more urgent topic in boardrooms”, Bain partners said. “However, the greatest operational value levers continue to be less sexy elements such as simply improving the way people work, honing strategy at the site level and enacting targeted changes to get the most out of their assets.
“By improving on the fundamentals global mining companies that we work with still regularly see production and efficiency gains of at least 15%, and often 20-to-30%, as well as safety and sustainability benefits.”
Bain said a survey of leaders at mining companies worth about $300 billion indicated three factors crucial to delivering operational excellence were workforce buy-in across an organisation, a strong understanding of what delivered value and stable, capable leadership.
“Unlocking the full potential of mining operations is becoming even more important, especially as the sector ramps up capital expenditures in the coming years amid the global energy transition” Bain partners said.
“Bain research has found that companies across industries with top-performing operational organisations deliver more than triple the profitable growth and total shareholder returns as their peers. As competition intensifies, mining companies that get operations right have a chance to significantly outperform the market.”
The Bain insights present a striking juxtaposition with financial services firm EY’s latest industry survey results, which suggest mining’s longstanding skills crisis is set to worsen “as retirements increase and new talent looks elsewhere”.
“The sector’s struggle to fill key roles, including in mine planning, process engineering, sustainability, closure and regulatory compliance undermines productivity and safety and threatens future supply,” EY’s Paul Mitchell says.
“Seventy-five percent of mining executives are not confident in their ability to resolve labour shortages for onsite operations.
“Attracting talent requires countering outdated perceptions of the sector, articulating its role in the energy transition and digital future, and showcasing the exciting roles on offer. Improving diversity, equity and inclusion can also help close skills gaps, and it is encouraging to see continued commitment to DEI objectives despite political headwinds.
“Partnering across the sector with universities and governments can also build new talent pipelines and agile education pathways.”
Mark Compton, executive director of the American Exploration & Mining Association, told IMARC 2025 “social acceptance” had never been more important to the industry and its connection with talent recruitment and retention in an era of fierce competition for the best and brightest in society was clear.
“That’s been talked about a lot at this conference, whether you use the term acceptance or social license. I don’t like the term license because it indicates that you’ve accomplished something, that you've gotten to an end point,” Compton said.
“And I think with social license, social acceptance, there never is an endpoint. It's always a work in progress. But whether it’s with the general public and making a connection between mining and their daily lifestyle, whether it’s with the communities in which a project operates, whether it’s with indigenous peoples, long gone are the days where you could just get a permit and go to work. Social acceptance is key to the success of any minerals project.”
Latest data suggests the US mining industry faces an estimated shortage of 80,000-100,000 skilled workers by 2029, including specialised roles in mineral processing and metallurgy. Australia's critical minerals expansion similarly requires significant workforce development to support projected growth in extraction and processing operations.
“In the United States we really have a workforce crisis,” Compton said. “It’s been estimated that half of the mining workforce in the US will be eligible to retire in the next five years. That is a very daunting statistic.
“We’re not training folks that we need, whether it’s in the industry or in other sectors. We expect government to permit projects in a more timely manner [but] they need a skilled workforce that understands mining.”
Will Wardle, who joined the International Council on Mining and Metals out of Durham University in England three years ago, says his short time at the ICMM has taught him mining is in need of “new skills and perspectives, with this demand offering new career opportunities and routes into mining”.
“Engineering and traditional roles remain vital in this industry, but now so does sustainability, community development, computing and communications amongst others. Mining is changing and the more inclusive it is of varied skills and backgrounds the more effective it will be in supporting the energy transition,” he says.
Now ICMM’s senior programme officer – environment, data and research, Wardle says the way the industry communicates is critical.
“No matter how much the mining industry evolves, unless young people can see opportunities, growth and purpose the talent gap will remain. The variety of the work I’m currently involved in, and the opportunities it brings, would have surprised my younger self and is rarely known by the next generation of talent,” he says.
“The industry must actively tackle this communication issue, and work to demonstrate to younger people its potential contribution to people, planet and prosperity. How mining tells its story is vital for attracting talent, diversity and the purpose-driven individuals needed to support society’s energy transition.”
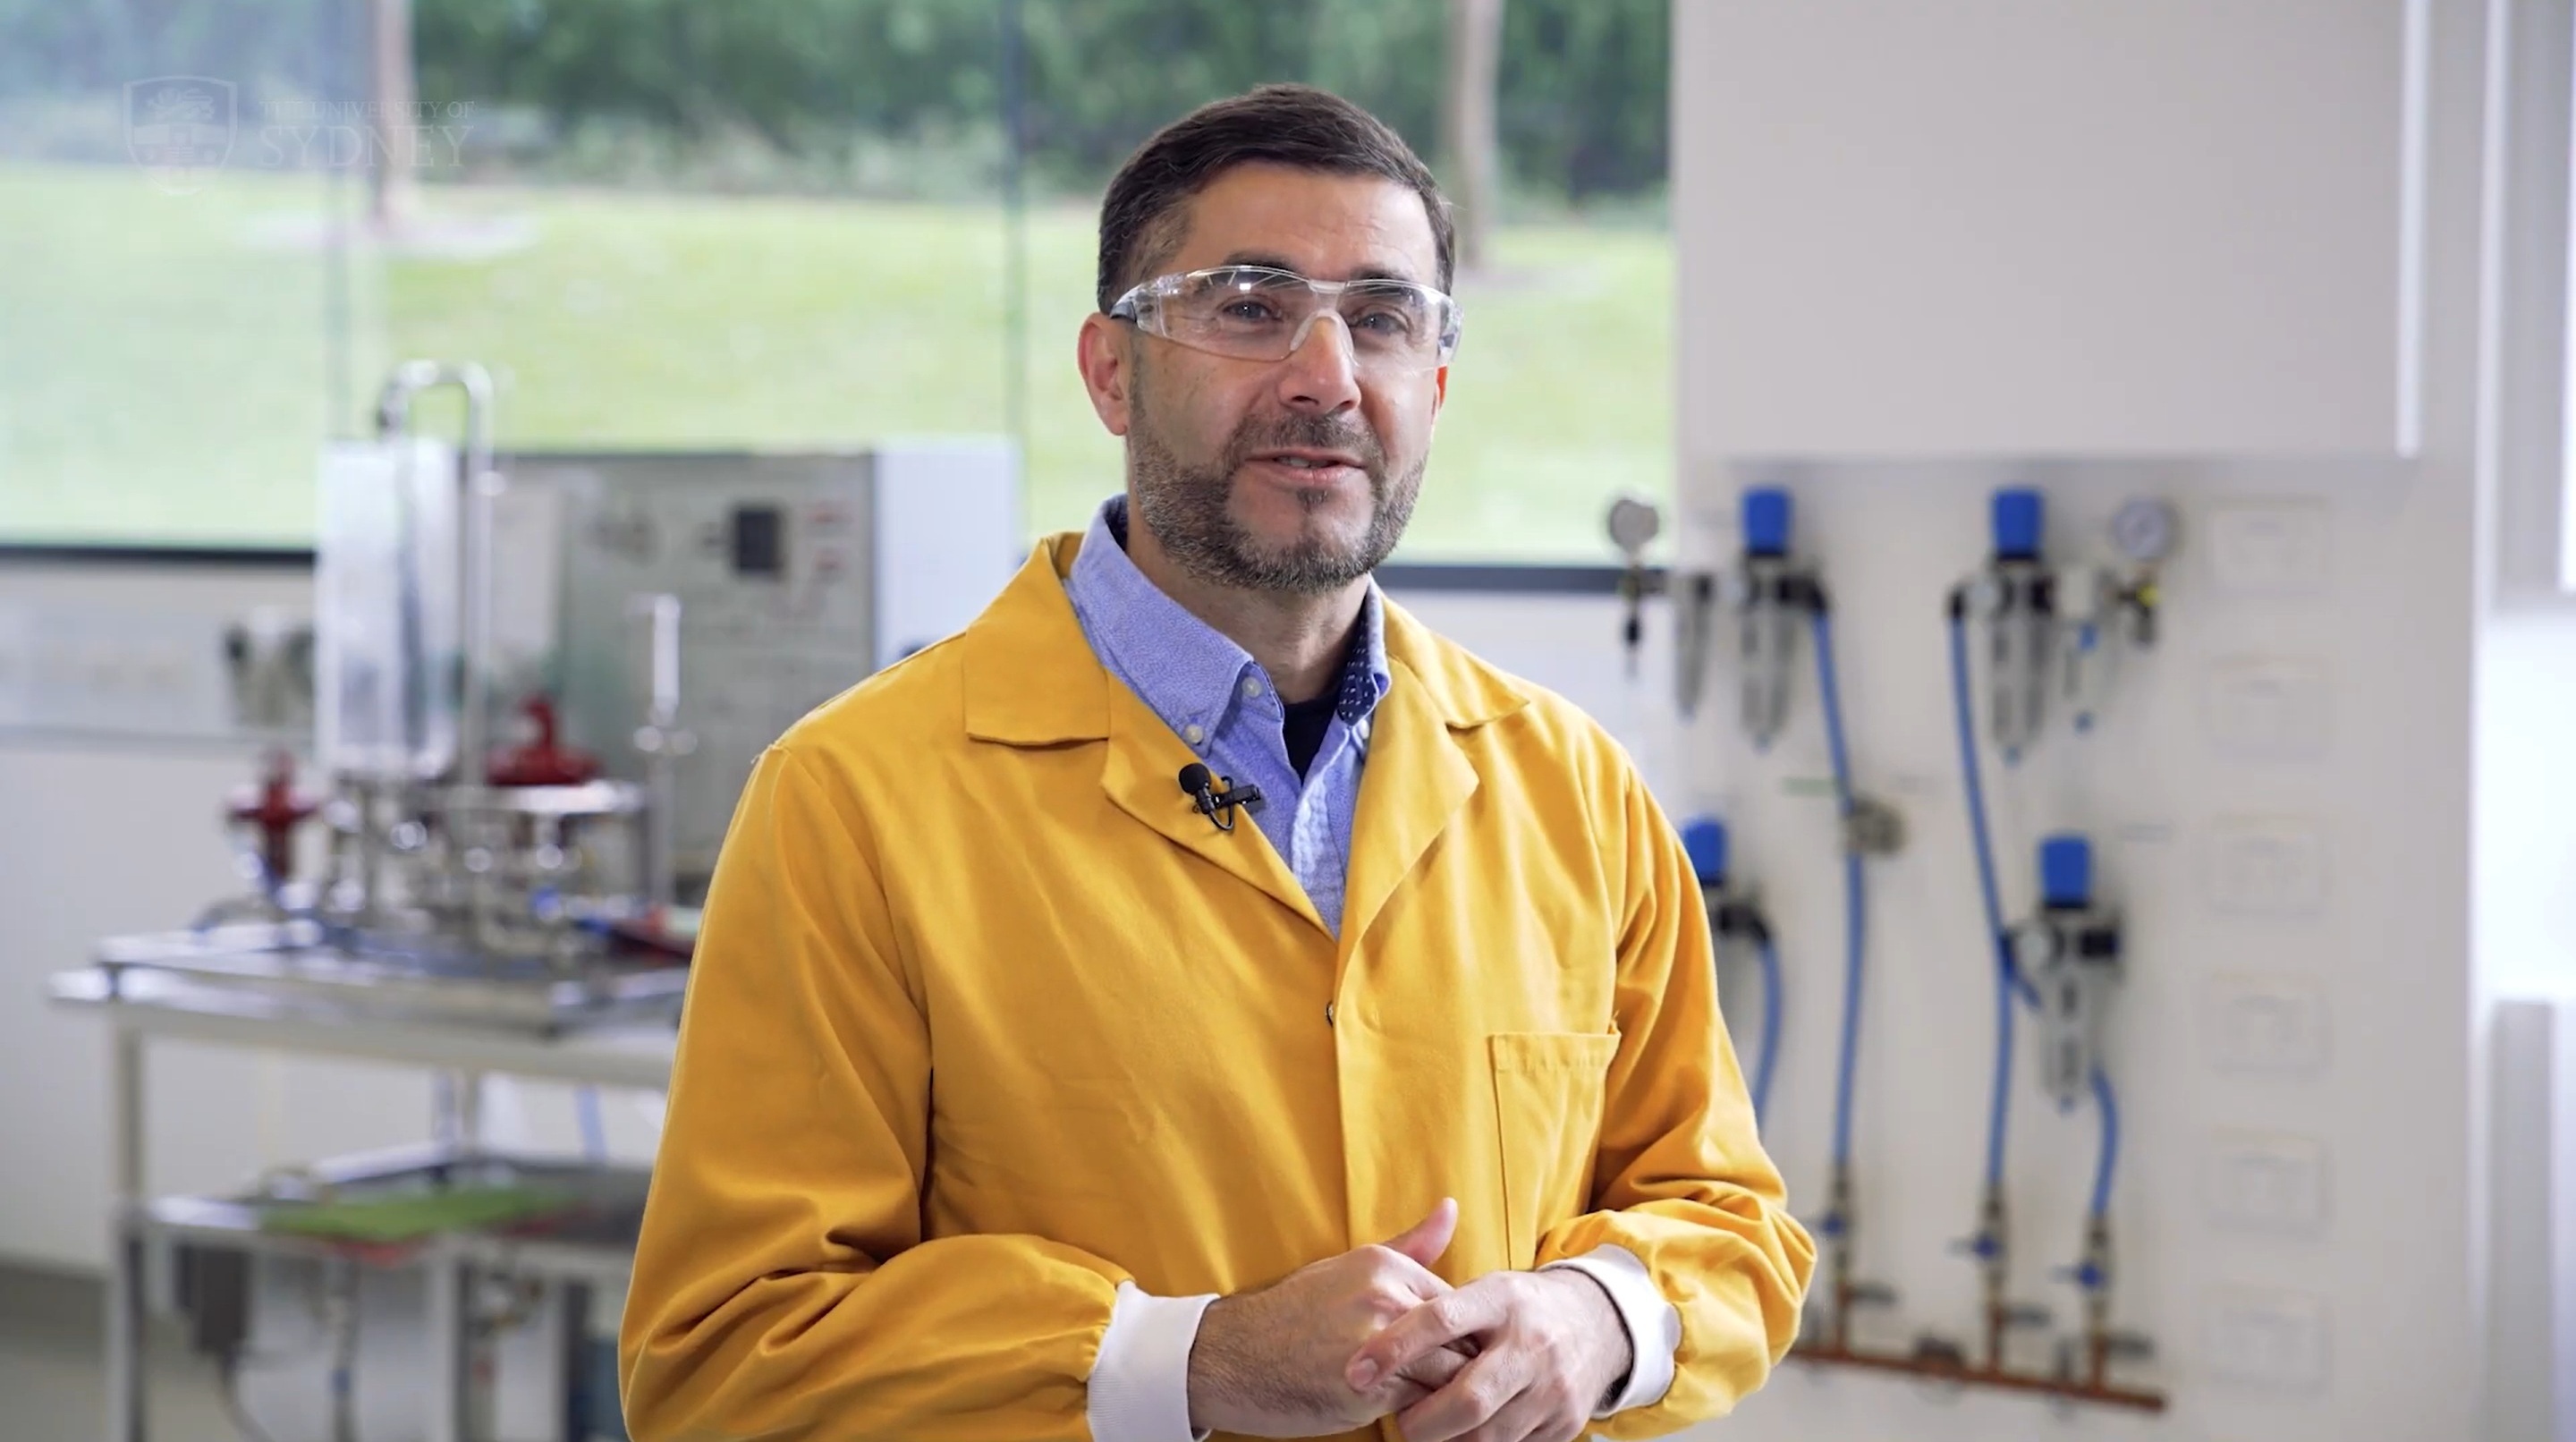
Professor Ali Abbas, associate dean at the University of Sydney Faculty of Engineering and Circular Australia’s chief circular engineer, said mining was at the core of the world’s circular economy challenge and people were the heart of that core.
“When we consider the large flows of materials we need process engineers and process engineering skill sets that are so much in demand in Australia,” he said.
“We still bring people from overseas to fill those gaps.
“[But this is a] shortage of specific skill sets that we are now experiencing all over the world.
“The scale problem is a big one.
“We work with major mining companies at the University of Sydney and they tell us it is a challenge to maintain people with these important skill sets and keep them in the regions.
“So we’ve got to be a little bit more sophisticated about how we solve this crisis.
“We’re trying to attack that at the University of Sydney by setting up a dedicated training centre for the future process engineers to go out and solve these big problems that we need to solve for circular economy.”
At the other end of mining’s value chain, University of New South Wales senior earth sciences lecturer Indrani Mukherjee said in a week in which Australia and the US announced a multi-billion-dollar critical minerals alliance, “it’s incredible how the geology departments at universities are like an ICU at a hospital”.
“It doesn't add up,” she said. A different type of communication was needed given past efforts had brought the industry to its current standing.
“There are lots of little bodies working incredibly hard to promote information, including geological outreach ... [but] the younger generation are not enthusiastic or passionate about Earth sciences.
“I think we need to be united. I think the efforts are too widely spread. They're stretched thin.
“And maybe no matter how good the intention is it's just not getting to the community as much as we'd like to.
“A more united front is one thing we could focus on.
“Diversity, too, is the elephant in the room. It’s not just geoscience, it’s science in general. And it’s not just an Australian problem. If half the world’s population don't see themselves having a career in geoscience then that's a problem.
“It’s not about equal outcomes. I stand here as a woman of colour in front of you all not demanding somehow that we have equal opportunity outcomes. I’m advocating for equitable opportunity. Everyone should get the opportunity to pursue the science that they love so much and then the outcomes can vary based on credibility.
“But that is something we need to focus on.”
Investing in a golden future
Mining companies’ exploration budgets have largely stalled, says a big global minerals engineering firm, which isn’t helping the search for quality copper, rare earths and other deposits. Available exploration funds are increasingly concentrated on a “narrow set of metals driven by short-term market opportunities”, says ERM.
Last year EY said achieving global decarbonisation targets by 2050 would require “a significant increase in the number of mines and volumes produced”. Capital raised for exploration had just declined year-on-year, “with budgets favouring gold over critical minerals like copper”.
“Lack of new discoveries and long permitting times add further complexity to the situation and put the energy transition at real risk,” the firm said.
IMARC 2025 was held amid a surge of junior fundraising activity, mainly in Canada and Australia. Of 112 financing and M&A deals worth more than US$22.1 billion announced so far in the fourth quarter of 2025, at the time of writing, 43% were gold-focused and 63% of the deal value (circa-$14 billion) centred on the yellow metal.
Stepping back to look at the bigger exploration and new mine-supply picture, MinEx Consulting managing director Richard Schodde said in the past 15 or so years 645 gold deposits of 100,000 ounces or more had been found – 1967 million ounces of gold – versus 54 copper deposits of 100,000 tonnes or more, or about 207 million tonnes of copper. In that same period 272Mt of copper had been mined. About 1470Moz of gold was mined.
While the industry wasn’t finding enough new copper in the ground to replace what was being mined, resource growth from existing mines and older discoveries meant the world wasn’t running out of the red metal – yet. “The problem is that eventually the old mines will close down and it takes time to develop new mines,” Schodde said. “And not all discoveries get developed. Only 41% of all discoveries in the world since 1950 have been developed. The average delay is 15 years.”
Schodde estimated half of all projects at prefeasibility or feasibility stage were currently stalled.
Human and regulatory resource constraints are at least a contributing factor.
Meanwhile, Schodde said, the world’s demand for copper had been doubling every 20-to-30 years.
“Over the next 25-to-30 years the world is going to mine more copper than what has been mined in all history,” he said, producing industry data showing forecast cumulative demand to 2050 of as much as 830Mt compared with the historical estimate of c800Mt copper mined.
“When you factor in the difficulties of converting a discovery into a mine there is a real risk that we won’t have enough new capacity to replace the old mines when they close down.
“This issue will begin to bite in a decade’s time.”


