
Mines & Money judges go for exception to the rule
- 10 December 2025

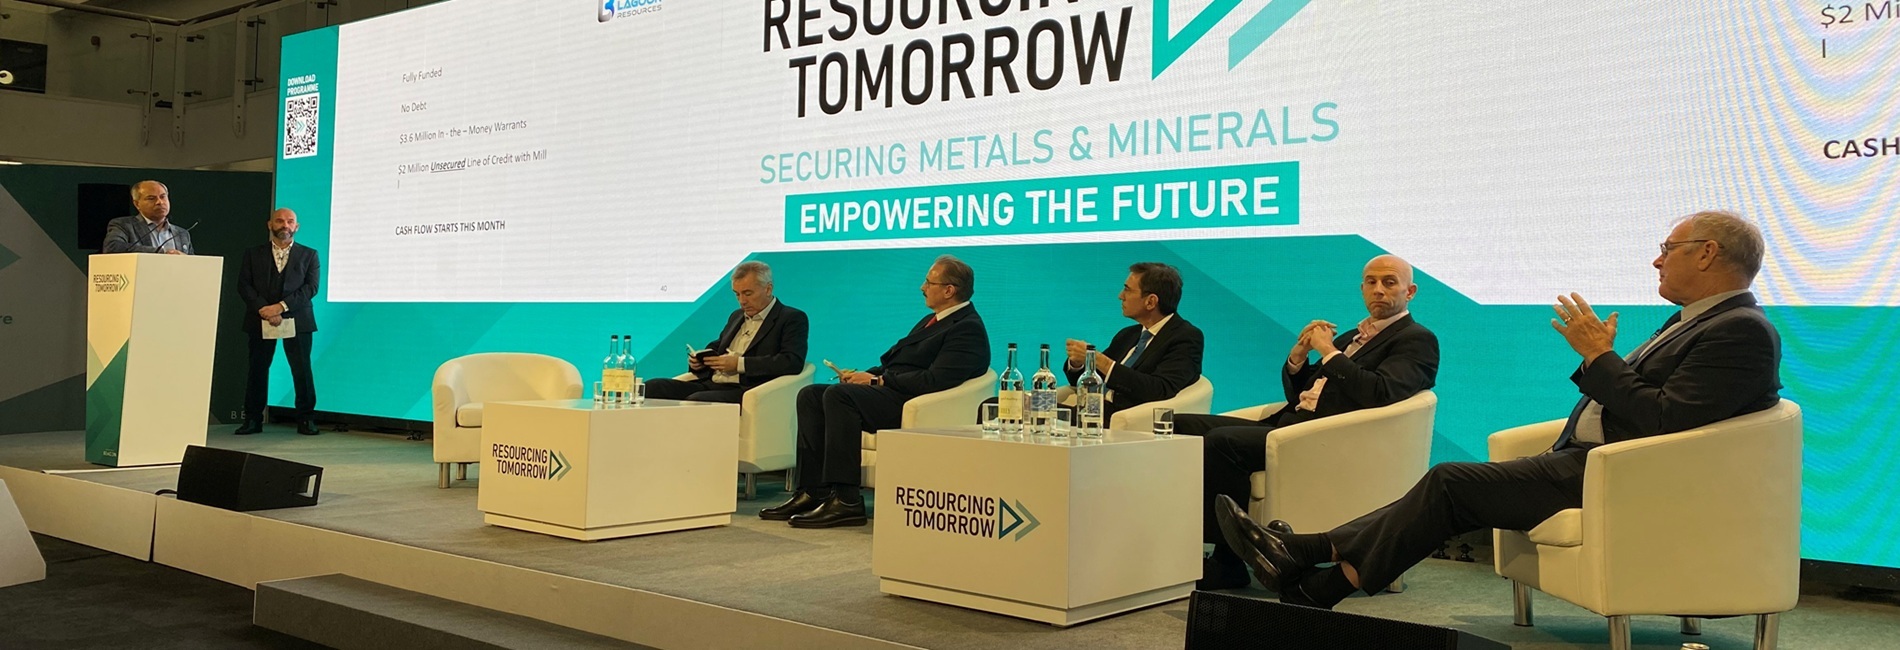
Bulks such as salt belong in private vehicles, was the view of Resourcing Tomorrow 2025 Mines & Money Pitch Battle judges, but this public junior impressed them with a compelling value proposition that was well outlined by CEO, Nolan Peterson.
Atlas Salt wants to build one of North America’s first new commercial salt mines in decades – a big underground “salt factory” at Great Atlantic on the Newfoundland and Labrador coast – and it won’t be cheap at the scale it envisions at about US$430 million of pre-production capex. That compares with the Toronto-listed minnow’s current circa-C$70 million market value.
But Xcelsior Capital managing director Cailey Barker, one of five highly seasoned investors on Resourcing Tomorrow’s judging panel, said he wasn’t “playing the stock [but rather] what’s going to make me more tangible money on the metrics that I can see in front of me”.
On that score, he said Atlas Salt came across as “very, very compelling”.
“It might not have the upside and sexiness of a gold stock but the metrics speak for themselves,” Barker said.
The format meant Peterson didn’t have long to do more than sketch out the numbers in Atlas Salt’s latest pitch deck, which details results of this year’s updated feasibility study. Suffice to say, proximity to an established seaport and other infrastructure, including hydropower, and the relative shallowness of a c25-year resource, underpin the company’s “first-quintile” economics.
“We have no diesel, no cyanide, no sulphuric acid: we have no external global commodities that are subject to price shocks or anything like that,” Peterson said.
“So we can come in at a low cost.
“And then, when it comes to shipping, our foreign competitors take, say, three weeks to get a boat from Egypt to Boston. It takes us three days. So we have a price advantage there. In all cases we are the lowest cost producer. When you have that advantage you have great flexibility to be competitive. I don't want to give away our strategy at this point but you could potentially put a lot of pressure on existing mines in North America that are operating in the high end of the cost curve.”
Atlas Salt sees a US$2.3-2.9 billion North American road de-icing salt market as its primary initial target within a multi-faceted global market worth maybe 10 times as much.
“In North America we don’t make enough salt currently to satisfy our needs,” Peterson said. “We import about eight-to-10 million tonnes per year. Our mine at full ramp up will produce four million tonnes.”
Atlas Salt will look to finalise a debt-funding package over the next six months so it can take a “direct financing de-risked project” to equity investors next northern summer.
“I also think bulk commodities are probably better served in private companies,” said Tembo Capital CEO David Street. “[The salt story] reminds me of bulks like phosphate where you can come up with a compelling case that you’ll displace existing production. In practice, it is hard to do that. So that would be my concern.
“But I did think the economics looked very interesting.”
While the London-based Street would like to see a smaller-scale start-up for Atlas, it got his vote.
Erez Ichilov, New York-based critical minerals expert and founder of Cedrus Arbor, thought Idaho-focused American Tungsten was a good speculative bet. The gold, salt and tungsten companies in the pitch battle definitely made for a “case of apples and oranges”. But he liked tungsten’s “dual-use” properties, filling a military need as well as other long-standing uses.
“You need tungsten for brain surgery and not just for weapons,” Ichilov said.
“With the need to re-industrialise and onshore build non-Chinese or Western supply chains you get almost a free ride for your civilian applications through the support from governments and institutions for the security component.
“It’s a good moment in time, especially in the United States and especially in well-established mining states within the US, for a brownfield project to go back into production in relatively quick time. It’s [American Tungsten’s IMA project] early stage. It’s risky. So we’re talking about a speculative investment. But if I had to speculate I would definitely go with this one.”
Baker Steel Capital Managers’ boss Mark Burridge split his vote between American Tungsten and one of two gold companies in the pitch battle, Blue Lagoon Resources. He – like gold major Newmont, apparently – was drawn to the exploration upside at Blue Lagoon’s now small-scale producing Dome Mountain project in British Columbia, Canada.
Pitch battle judge number five, Rick Rule, kept his chequebook in his pocket.
Rule, who these days presides over Rule Investment Media after decades in private and public funds management, said his “suspicion” was that Atlas, American Tungsten, Blue Lagoon and Canadian gold explorer Abcourt Mines would all probably do okay in the current market. But he was going to hold back “this round”.
“In bulk commodities like salt I prefer those to be private as opposed to public,” he said.
“I’ve found public markets are ungenerous with intelligent business plans and being private obviates the need to subject yourself to the idiocy of public markets.
“With regards to the other three, the idea of bootstrapping is always sexy to entrepreneurs and it was sexy to me when I was a young man.
“What I’ve learned in my old age is that anything that can go wrong with a big mine can go wrong with a small mine, but a small mine can never make you big money.”


