

Resourcing Tomorrow 2025: Six vital conversations
- 9 January 2026

December’s major Resourcing Tomorrow conference in London promised to drill into six vital industry themes and in these areas and more the event put the writing on the wall for 2026.
Key topics on the 2025 agenda were:
- Critical minerals at the crossroads of geopolitics
- Supply chains for defence, EVs and AI
- Circularity and sustainability beyond ESG
- Technology and the AI, data and innovation transforming mining
- Financing, investing and fast-tracking mining projects
- Addressing workforce challenges and opportunities
Mining CEOs such as Alcoa’s William Oplinger, Fortescue’s Dino Otranto, Hindalco copper’s Rohit Pathak, Torex Resources’ Jody Kuzenko and Weir’s Jon Stanton joined the heads of the International Council on Mining and Metals, International Copper Association and Minerals Council of Australia – Rohitesh Dhawan, Juan Ignacio Diaz and Tania Constable, respectively – and leaders from Vale, Codelco, Ivanhoe Mines, Freeport-McMoRan, Anglo American and Endeavour Mining on the stage.
Finance sector luminaries and gurus Karina Danilyuk, Evy Hambro, Rick Rule, Dominic Raab, Frank Giustra, Bert Koth, Mark Burridge, Cailey Barker and James Richards brought investor gravitas.
Government leaders and representatives from more than 40 countries added to Resourcing Tomorrow’s unique multifocal mining lens.
Shifting global geopolitical, social and technological settings were, as expected, a big focus at the event.
Critical minerals at the crossroads of geopolitics
Back in Washington, USA, after speaking at Resourcing Tomorrow 2025, Centre for Strategic & International Studies Critical Minerals Security Program director Dr Gracelin Baskaran said 2025 was a year unlike any other for the mining industry.
“Critical minerals have become embedded in nearly every major policy debate in Washington: defence readiness, energy security, industrial policy, trade and alliance management,” she said.
“At the same time, it’s been a year of sharp contrast.
“We've seen historic levels of policy attention, new financing tools and deeper engagement with allies. But we’ve also seen persistent market volatility, long project timelines, fragile demand signals and strategic competitors continuing to weaponise key mineral supply chains.
“There’s a growing recognition in Washington and beyond that minerals are not just commodities. They’re in fact strategic assets essential to our security. They sit at the foundation of our defence industrial base, energy resilience and technological leadership.
“When access is secure nations compete and when it’s not they become vulnerable.
“Looking ahead to 2026 the stakes only rise. The cost of delay, whether in permitting, financing or coordination, continues to grow. The luxury of time is not something the sector or [the US] has.”
Adam Burstein, strategic & critical materials technical director in the US Government Office of the Secretary of Defense, told Resourcing Tomorrow 2025 a frenzy of policy directives had translated into (relatively) significant coordinated action in the first year of Trump 2.0. “Not only do we have now a whole of government effort to get after the problem but we've really seen our Congress help to resource it,” he said. “We have $5 billion for critical minerals just in the office that I represent. We have a billion dollars that underpins $100 billion in loan authorities through the Office of Strategic Capital in our office. We’ve seen $2 billion come in for stockpiling, which represents an eightfold increase over the aggregate amount that the stockpiles received since the end of the Cold War. And we've seen a flood of resources across government agencies.”
Former US assistant secretary of state for energy resources, Geoffrey Pyatt spoke on a Resourcing Tomorrow panel with Baskaran on geopolitics and global fragmentation impacts on mining. He joined in a non-government role, as head of McLarty Associates’ energy and critical minerals practice, and said: “Compared to my first two Resourcing Tomorrows there was no need to argue for the geopolitical importance of critical minerals supply chains. China is writing out talking points there.
“But as I emphasised in the panel [discussion], we will only reduce our vulnerability through concerted international partnerships, leaning on allies and partners like Japan, Canada, Australia, Korea, India and the EU that share our concerns and are ready to put government resources into supply chain diversification.
“My takeaway from this year is that we are making considerable progress but there is work to do bridging industry and government perspectives.”
London law firm White & Case says 2025 put mining and metals at the heart of geopolitical competition. This year participants face a decision: “Be a pawn or a player in a business cycle and environment structurally driven by a geopolitical race for mineral security and national power.
“Many resource-rich governments are no longer content with the traditional extract and ship model. They are using regulation and export controls to force more value to be captured at home. Indonesia’s nickel export ban is the most prominent example, used to catalyse a domestic mid- and downstream processing industry.
“These policies are colliding with pushes from the US and the EU to de-risk critical minerals supply chains by bringing processing and refining back to their own territories.
“The result is a more crowded policy space.”
More crowded and noisy this former policy vacuum may well be, however, Rothschild global mining and metals head Karina Danilyuk said there was only one genuine elephant in the room.
“There is lots of capital being deployed by governments, at least on paper, into the sector, driven obviously by geopolitical competition,” she said.
“But there's only one sovereign in the world today that actually has a long-term strategy around this and this is China.
“Everybody else is just playing amateur dodgeball.
“[They are] throwing money at things that are either approximate or visible or they make headlines, whereas China has taken a very long-term view and as a consequence of that has consolidated the majority of rare earths processing, and therefore is controlling that market; is controlling the lithium market through subsidies throughout the value chain ... and [has] a substantial share of the copper smelting markets, which has driven the rest of global copper smelters into complete disarray with negative TC-RCs over the past couple of years.
“And I think we will continue to see that.
“That is very much about subsidising through the value chain. It's about supporting national champions that are going out and putting their foot on resources globally and subsidising processing and concentrating that in China.
“I don’t think anybody else comes close to having that type of control and long-term strategy.”
Supply Chains for Defence, EVs and AI
White & Case says unprecedented government policy support for new mining projects and trade policy volatility reflects the geopolitical urgency of securing critical minerals supplies.
“This race to build or source minerals and metals from outside of China and without the involvement of Chinese sponsors has begun to create pricing premiums for rare earth elements,” it says.
“North American and European automotive and defence OEMs panicked last spring and summer over China's export controls and their limited stockpiles. Just-in-time supply chain management has become a material business risk. While REEs are an exceptional case, markets are structurally shifting from the pursuit of green or analogous premiums for security premiums, even as the EU doubles down on CBAM [the EU’s Carbon Border Adjustment Mechanism].”
Peter Handley, Hague Centre for Strategic Studies adviser and senior fellow with the European Initiative for Energy Security, told Resourcing Tomorrow 2025 the EU’s critical raw material supply journey started with decarbonisation and digitalisation goals. “But over time what’s come to the forefront is defence and security. It’s economic security, it’s preparedness, it’s resilience.”
The new ReSourceEU Action Plan put “money on the table” (circa-US$3.5 billion) with a promise of more. Handley said a European Minerals Investment Network (E-MIN) was also vital because it put relevant parties – public and private investors, industrial offtakers and project developers across Europe and allied countries – around the same table. What also needed to happen was “something that changes the behaviour of companies so that they pivot away from the lowest cost commoditisation of critical materials and are prepared to look at [mechanisms] that put a value on the resilience in either producing in Europe or producing with friends”.
Federation of German Industries (BDI) International Cooperation, Security, Raw Materials and Space deputy department head, Anne Lauenroth said resource security and national security, or European security, were “two parts of the same coin”.
“I think both the German government and also the European leadership have acknowledged this,” she said.
“What we now are trying to do is build up new capacities in an environment which is marked very much by high cost structures. Also, still challenges with regard to permitting, with regard to regulation, and in general still too few capacities when it comes to critical minerals.
“From the government point of view we have seen also a change in our own strategy, especially with the establishment of the Raw Materials Fund in Germany, which is up to €1 billion, and co-investing with equity into projects.
“We still need this to be operationalised, that’s true.
“A big challenge is the concentration and the bottleneck of the midstream and what I see with concern is that while we still have quite good strategic assets and midstream companies in Europe, we have the danger of losing them and also losing the capacities.
“The comparative advantage of German and European industrial players in this mix is quite important because we are in this technological competition and we have a good base, but we really need to be very precise and use our instruments in a good way.
“So while we build up new capacities we also need to see how we can protect the existing production capacities that we have. Obviously the geopolitical weaponisation is heavily concerning us.
“This should worry us and be speeding up our efforts.”
Dutch Ministry of Economic Affairs raw materials strategy adviser Allard Castelein nodded: “Most important at this juncture is recognising how challenging and difficult this predicament is we're in and ... setting about it rather than continuing to evaluate and intellectualise at 30,000 feet.
“The Netherlands seeks to turn it around and call it an opportunity. There’s an opportunity to create greater resiliency. The Netherlands in particular can offer fantastic logistics. Our infrastructure and ports are second to none. The connections with the hinterland, with the industrial clusters in Germany and in Belgium and in France and even Switzerland and Italy, are second to none. We’re seeking to establish strategic stockpiling. We’re seeking to create opportunities to bring production facilities back into the country. The industrial clusters, as I alluded to, are very, very strong. They're very well interconnected with other industrial clusters.
“The Netherlands is a small country yet we’re one of the most important investors in the US, so we have very strong international ties.
“We will need to change our understanding of the market dynamics because if we continue to do what we've always done we're not going to get a different outcome.”
US investment bank Morgan Stanley sees technology, more than anything else, at the core driver of these market dynamics. It was “moving to the centre of a multipolar world and embedding itself in the global balance of power”.
“The AI race is effectively becoming bipolar between the US and China, shaped not just by model capability but by access to power, tech talent, semiconductors and critical minerals,” the bank says.
“Europe sits in the middle of this competition, balancing security, welfare and competitiveness while it ramps up defence spending and remains exposed to Chinese supply chains.
“As AI, defence technology and advanced manufacturing converge, technology choices are forcing countries and companies alike to make trade-offs.”
Circularity and sustainability beyond ESG
Ana Gabriela Juarez, president of CTA Environmental Consultants, said geopolitical uncertainty, trade tensions and shifting defence and technology needs were placing enormous pressure on supply chains at a time when global demand for certain minerals was growing faster than miners could find, permit and develop new mines.
“This combination makes one thing very clear,” she told Resourcing Tomorrow 2025.
“Circularity is becoming essential. It’s not an option anymore.
“Across the industry we are seeing a real potential in reprocessing of tailings and historical waste, recovery of high value by-products and critical metals, new leaching, mineral processing and bio-recovery technologies and partnerships that close loops between mining, manufacturing and recycling.
“Circularity might be one of the most strategic levers we have to secure responsible, resilient supply in a world that cannot wait 20 years for new production.”
The conference heard it was a lever that continued to come with complex technological, cost and regulatory considerations.
Bill Cobb, chief sustainability officer at copper major Freeport-McMoRan, said the key factor was, “economics, economics, economics”. Mining and metals company business models were evolving to convert more waste into value and to establish more contact points with a nascent urban mining sector. The group’s €400 million CirCular project at Huelva in Spain, due for launch in the first quarter of 2026, would recover non-ferrous metals including copper from electronic and electrical equipment waste at scale.
“That is the traditional circular economy kind of thinking in terms of being able to recycle content if you can get it out of the economic stream and reintroduce it as new copper,” Cobb said.
“There’s another way of thinking about circularity and that is turning waste materials into new product. And for us we have 40 billion pounds of copper locked in waste stockpiles. We are at about 200-to-300 million pounds of copper a year [from leaching of low-grade stockpiles]. Our target is 800 million pounds. That’s a new major copper mine and it's basically capturing waste material at the mine site.”
These and other options presented both short and long-term economic questions.
“If you've got a major copper operation and you've got a molybdenum recovery circuit, for example, you have got the potential for rhenium recovery,” said Cobb.
“But the rhenium market’s not all that big.
“If you’ve got a major copper operation one of the questions is, do we flood the global market with rhenium production? And if you do, you are going to drive the price down. This brings us back to, it's the economics question.
“We also talk about reprocessing tailings [and] creating building materials. A big building materials facility might consume 1000-to-2000 tonnes of tailings per day and if you’re milling 10,000-to-15,000 tonnes a day that's a pretty significant offtake of your material.
“If you're a 200,000 tonnes-a-day copper operation it’s absolutely insignificant to the tailings structure.
“So the optics look good but when you think about the economics of the copper operation that building products business is rounding noise.”
Favourable economics helped tip significant quantities of iron, steel, aluminium, copper and lead into the global circular economy. Cobb said other equations needed work.
“In the United States we’ve had multiple administrations trying to figure out how you get people to get rid of their extra cell phones. But you can't do it. And so it’s a significant impediment,” he said.
“We the consumers are the major impediment because if you can’t harvest it you don’t have the supply to put into secondary processing.”
Resourcing Tomorrow heard more stories highlighting spasmodic circular tilts by industry.
World Resources Forum managing director Dr Mathias Schluep believes stronger international collaboration is urgently needed to establish coherent global governance of resource use across product lifecycles, from extraction to trade, use and recovery.
“Material-flow data remains fragmented and differing methodologies and reporting obligations weaken transparency, obscure risks and undermine accountability,” he said.
“A shared measurement framework is essential to monitor and compare extraction volumes, environmental and social impacts, trade flows and material stocks. Without coherent metrics, efforts to strengthen resilience and deliver sustainability and supply security will remain limited.
“Interoperable indicators at extraction would enable due diligence and responsible sourcing, while shared targets at use and post-use stages would build trust in circular products and recycled materials.”
Schluep said beyond new material supplies ongoing convergence of the traditional circular economy and mining worlds was crucial to “sustainability in our world”.
“The circular economy community has looked at mining ... as the beginning of the linear economy and I think this mindset has to change,” he said.
“I see an opportunity for the industry here because actually being at the beginning of the raw material [supply chain] creates a lot of knowledge about the material. It creates a lot of decision power about what happens with the raw material later on. So I think mining should see itself in the centre of the circular economy.”
On the subject of evolving business models, Schluep said “materials as a service” could come into focus sooner rather than later.
“We have examples in the chemical industry ... of concepts like chemical leasing [where] you don’t necessarily sell your chemicals, you lease them to somebody. That changes of course the concept of price and businesses and even how you perceive the raw material.
“It can change your mindset. Do you want to deliver your raw material in a certain [part of the] economy or not?”
Tech revolution: AI, data and innovation transforming mining
Technology is changing mining inside and out. More than US$14 billion of global mining and metals tech financing and M&A in the past five years points to a perceived major shift in the industry’s scale and pace of technology adoption over the next decade.
The CEO of London-listed Weir, which spent $800 million on an Australian mining software vendor in 2025, has repeatedly highlighted the upside for miners – in terms of productivity, cost and higher metal output – from leveraging available tech. Jon Stanton told Resourcing Tomorrow 2025 extensive voice of customer feedback indicated the industry’s wants were simple, but potentially transformative. “It is helping move less rock, use less energy, use water wisely, create less waste and use digital capabilities to really boost and turbo-charge what we can do in terms of hardware. Those five things drive our technology and innovation roadmap.”
Former Rio Tinto and Barrick Mining senior manager Kendall Cole-Rae, who spoke at Resourcing Tomorrow 2025 in his capacity as expert-in-residence at Fleet Space Technologies, said the industry faced a “critical inflection point” vis-à-vis technology and innovation.
“To meet rising global demand we must fundamentally alter how we explore, develop and collaborate,” he said.
“This requires embracing new ways of working powered by real-time digital intelligence to unlock the known bottlenecks in our processes – from early exploration to final development – to drive a step-change improvement in performance and competitiveness across the entire value chain.”
Cole-Rae echoed the words of others at the conference, such as International Council on Mining and Metals CEO Rohitesh Dhawan and Worley UK resources vice president Darryn Quayle, in saying this tech-led shift in performance was key to unlocking new capital and community and government support.
“The challenge is to make mining cleaner and more acceptable, so projects can be approved and operated responsibly, by deploying new technologies and methods,” Quayle said.
“The world expects mining to minimise environmental impact and respect communities. Our social license to operate depends on it.
“If we dramatically reduce our footprint, we’ll get permits faster and face less opposition. If we don’t, projects will stall or fail to be approved at all.”
Dhawan said mining’s “golden age of mining innovation” should be in full swing. The industry had never needed innovation more. However, resistance to change was widely stalling progress.
This is cultural work – deep, long-term, values-driven change,” he said.
“And it needs to start now. That’s as much a call to action as a reminder to myself as this may need an industry-wide intervention.”
Meanwhile, the AI, automation, robotics and electrification changes promising mine owners and miners themselves a better future are also driving escalating material demands.
Morgan Stanley says data centres could account for 2.1% of total copper demand growth in 2026.
“On our commodity team’s estimates data centres consumed about 500,000t of copper in 2025, which is expected to rise to 1Mt by 2027 and 1.3Mt by 2028,” bank analysts say. “This represents about 1.5% of demand currently. However, this could reach 3.3% by 2028, behind EV demand at 5.6%.
“Data centre estimates could also continue to rise, fuelling copper demand, with Morgan Stanley strategists expecting global data centre power to rise by 19GW in 2025 and 27GW in 2026. The team's estimates have been rising since their initial early 2024 analysis.”
Evy Hambro, global head of thematic and sector investing at asset management giant BlackRock, said, again, time and speed were essential elements in connecting technology with material-based value chains.
“When you think about the digital age that we’re going into very, very rapidly. it is going to take more and more of these materials to allow countries to be competitive,” he said.
“The weaponisation of supply chains is what is going on behind the scenes.
“It is important to win that race and countries are going to pay anything to ensure that. It’s obviously very good for existing producers, which is where we’re positioned.”
Financing and fast-tracking new mines
Elephants are said to have long memories but it wasn’t the reason Worley vice president Darryn Quayle was standing next to one while imploring mining leaders to remember what underpinned the past faith of investors, communities and governments in the industry in a keynote address.
“Mining is expected to deliver the raw materials for a future the world wants, but right now we are not on track to supply them,” Quayle said.
“If the 19th century ran on coal and iron, the 21st century will run on copper, lithium, nickel, cobalt and rare earth elements – the critical minerals needed for clean energy technologies and advanced digital devices. Demand for these minerals is skyrocketing. To support electric vehicles, AI data centres, large-scale batteries and all the infrastructure of a low-carbon economy, we will need far more of these materials than we produce today.
“Yet our industry’s current trajectory doesn’t give confidence we’ll meet that demand. Not with business as usual.
“Unless we dramatically change how we mine and finance mining we risk falling short. In plain terms, if we carry on as we have been we will not supply the metals needed for the future society is building.
“Meeting this gargantuan demand requires a fundamentally different approach. We have to recapture the ingenuity of our forebears and apply it to today’s realities.
“We have to address the elephant in the room.
“That’s why this conference is called Resourcing Tomorrow.”
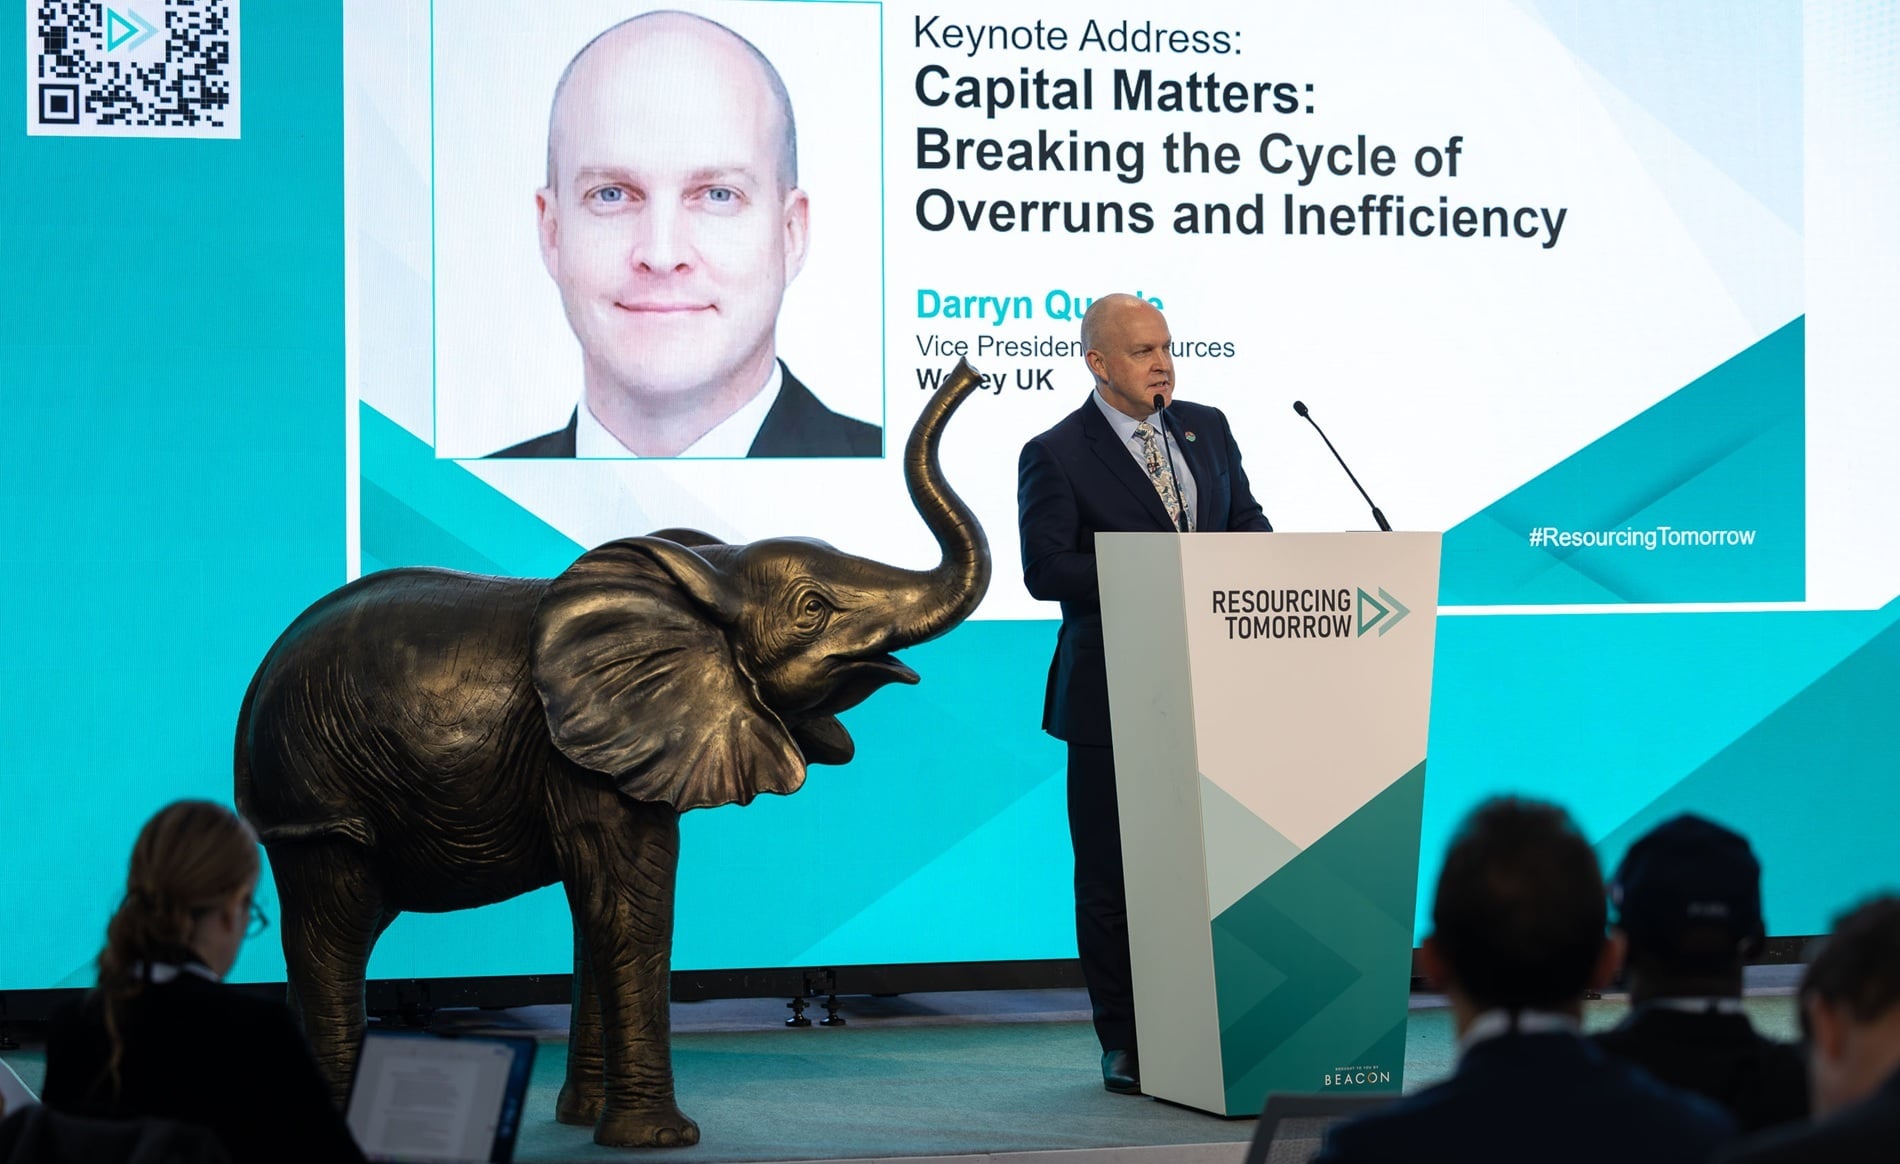
Quayle said a need to compress project timelines and build more agility into operating plans meant the industry really had to look harder at different ways of planning and delivering mines and infrastructure. “How do we make mining cleaner and easier to approve?” he said.
“It takes far too long to bring a new mine into production.
“Entire tech revolutions happen in 15 years. Yet that kind of delay is normal in mining.
“We must find ways to go from discovery to production faster—not by cutting corners on safety or community relations, but by planning smarter and executing more efficiently.
“We [also] haven’t been delivering projects on time and on budget. It wasn’t always this way. A few decades ago, many mining projects came in on schedule and under budget; if a company promised a mine by 2025 for $1 billion, investors had reason to believe it. Today that trust has eroded.
“Only about one in six mining projects is completed as planned. The vast majority blow past budgets or deadlines, or both. On average, a project ends up costing around 50% more than initially estimated and starting production years late.
“From an investor’s perspective, this is alarming. If nearly every mine project requires significantly more capital and time than promised, investors get skittish. They demand higher returns to compensate for the risk, or they invest elsewhere, or they wait until a project is finished before getting involved. In all cases, less capital is available for new mines, and what does come is more expensive.
“It’s telling that industry surveys now rank project execution as one of the top risks in mining, above things like geopolitical instability. If we as an industry can’t predict our own outcomes, why should financiers bet on us?”
Quayle said mining’s shifting environmental and social challenges also contained opportunities.
“If we dramatically reduce our footprint we’ll get permits faster and face less opposition,” he said.
“If we don’t, projects will stall or fail to be approved at all.
“Take mine waste, for example, especially tailings. For over a century our solution has been to store tailings as a liquid slurry behind dams, creating huge tailings ponds. This is increasingly untenable. Tailings dam failures have caused devastating environmental damage and loss of life. Even without failures these vast waste impoundments are permanent liabilities, requiring monitoring long after a mine closes. Public tolerance for this legacy is wearing thin.
“What if we could eliminate tailings dams? What if we didn’t bring so much waste to the surface in the first place?
“That’s the kind of step-change we need in mining’s environmental performance.”
Addressing workforce challenges and opportunities
London-based EY’s top 10 business risks and opportunities for mining and metals in 2026 had workforce outside the top five but it seems likely it will move up the table in coming years.
“Mining’s longstanding skills crisis is set to worsen, as retirements increase and new talent looks elsewhere,” the firm says. “The sector’s struggle to fill key roles, including in mine planning, process engineering, sustainability, closure and regulatory compliance undermines productivity and safety and threatens future supply.”
A staggering three-quarters of mining executives surveyed by EY in the course of compiling its latest outlook report said they were “not confident in their ability to resolve labour shortages for onsite operations”. EY global mining and metals lead Paul Mitchell said: “Attracting talent requires countering outdated perceptions of the sector, articulating its role in the energy transition and digital future, and showcasing the exciting roles on offer. Improving diversity, equity and inclusion can also help close skills gaps, and it is encouraging to see continued commitment to DEI objectives despite political headwinds. Partnering across the sector with universities and governments can also build new talent pipelines and agile education pathways.”
Resourcing Tomorrow 2025 speaker and Mining Association of Canada senior vice president, Ben Chalmers said a projected shortage of 100,000 workers in the country’s mining industry over the next decade wasn’t shifting despite the resources being thrown at the issue and success in bringing more women and indigenous people into the industry. “Unless we can find new ways of attracting talent, including women and visible minorities and others, we are not going to have the workforce,” he said.
“Our engineering schools are not full in Canada in terms of mining engineering. Our geology schools have ample capacity to take more students and we're not getting the recruitment in these areas.
“We have an organisation in Canada called the Mining Industry Human Resources Council that manages our labour market needs, does labour market research, does recruitment, handles our trades credentialing. We’re working with them as well as other partners including the World Gold Council and ICMM on a campaign called Mining Needs You and it’s aimed at recruiting young people into professions and trades that mining needs.
“We have partnered to try to reach a million students a year to help them understand the career opportunities that exist in our industry.”
Resourcing Tomorrow heard about capital, regulatory, technology and speed gaps between strategic materials frontrunner China and the best of the West. What needs to be scrutinised more is the mining education and skills gap.
The US Centre for Strategic & International Studies’ Gracelin Baskaran, whose father chairs a Detroit university geology department, says she has heard directly how geology, environmental science and engineering graduates in the country are not moving to the mining sector.
“Catching up in this area will require a significant increase in capacity building and financing,” Baskaran says.
“This is for two reasons. First, academic programs largely succeed or fail based on available funding – particularly for research and scholarships. Second, there is often a lack of expertise to build these programs. This will require bringing in both skilled industry experts and faculty from mining programs around the world to cross-pollinate knowledge and build these programs.”
CSIS research has observed that more than half the current domestic mining workforce in the US – some 220,000 workers – will need to be retired and replaced by 2029.
“This number stands in stark contrast to the total of just 327 degrees awarded in 2020 in mining and mineral engineering and a 39% net drop in graduations in the United States since 2016.
“University programs tasked with creating this workforce have also been decreasing, with the number of mining and mineral engineering programs in the US dropping from 25 in 1982 to 15 in 2023. This is in stark contrast to China, which has over 38 mineral processing schools and upwards of 44 mining engineering programs. Central South University, China’s largest mineral processing program, has 1000 undergraduates and 500 graduate students alone ready to accomplish China’s mineral ambitions.”
Baskaran wrote at the start of 2026 that if there was an enduring lesson about US critical minerals vulnerability to be taken from the 20th century it was that mineral security came from industrial policy not stockpiles.
“Repeatedly, US policymakers treated stockpiling as a discrete technical solution rather than as one component of a broader industrial strategy,” she said.
“This narrow framing masked deeper vulnerabilities: erosion of refining and conversion capacity, offshoring of technical expertise, underinvestment in exploration and processing, and fragmented coordination between government and industry.
“Throughout the historical record, stockpiles proved valuable as short-term shock absorbers, but they never functioned as a substitute for durable industrial capacity.
“Stockpiles could cushion temporary disruptions, stabilise markets, or buy time during crises, yet they could not replace resilient supply chains, domestic and allied processing capacity, skilled workforces, or transparent and well-functioning markets.
“Where these broader systems were weak or absent, stockpiles merely delayed the consequences of structural dependence.”


