

Resourcing Tomorrow 2025: The long and the short of it
- 5 December 2025

The chickens are coming home to roost, according to Rick Rule, the wily American natural resources investor who says at age 72, after exiting private and public funds management to run his own race, he’s become “demonstrably more patient” as a cheque-writer.
“I’m delighted to be free from the circumstance where my efforts are directed to somebody's quarterly cash bonus and more directed towards risk-adjusted internal rates of return in a five or 10-year time frame,” says Rule, who’s no doubt done well on both fronts.
One of the most conspicuous investors in the mining space over the past 30 years partly blames institutional investors and short termism for chronic under-investment in exploration that has left the industry’s project cupboard understocked with high-quality development options, a prominent theme at this year’s Resourcing Tomorrow conference in London.
“We have under-invested systematically in exploration for closer to three decades than two decades, and the chickens are coming home to roost with regards to that,” Rule says.
“When you look at the major companies and you look at the way that they've attenuated both their exploration spend but also their investment in human resources around exploration, what they have done whether they admit it to themselves or not is they have outsourced exploration. The consequence of that is that the amount that they are willing to pay for a real discovery is mindboggling – really, truly mindboggling.
“[But] I think it’s important to say that in the five-year term, maybe even the 10-year term, we have what's mostly an unsolvable problem.
“We’re 30 years late coming to the party in exploration. We have a lot of deposits in the world that are drilled off but at today’s cost of capital and today’s copper prices they don’t make any sense, which is a challenge.
“The deposits that are economic are very, very large and they’re beyond the reach of mortals like me. You have these very large deposits that are US$7 billion builds today, except they're not. We think they're $7 billion builds because two years ago they were $7 billion builds. They’re $9 billion builds today and the inflation and construction costs are such that next year they’ll be $10 billion builds and then $12 billion builds.”
Resourcing Tomorrow 2025 heard about escalating, expensive M&A, particularly around copper; climbing project capital intensity, particularly around copper; concurrent surging copper demand; and generally out-of-control project development timelines. The conference heard about the flaring intersection of public and private capital in what Ukraine government economic deputy minister Yegor Perelygin deftly referred to as “the so-called Western world”. It heard from Rule and others about the short-termism in that part of the world. “We [society] have become, pretty much everywhere, far, far too short term,” British advertising guru Sir Martin Sorrell told the conference.

Lots and lots of chickens.
The elephant in the room: China.
“There is lots of capital being deployed by governments, at least on paper, into the sector, driven obviously by geopolitical competition,” Rothschild & Co global head of mining and metals, Karina Danilyuk, said.
“But there’s only one sovereign in the world today that actually has a long-term strategy around this, and that is China.
“Everybody else is just playing amateur dodgeball, throwing money at things that are either approximate or they make headlines, whereas China has taken a very long-term view and as a consequence of that has consolidated the majority of rare earths processing and therefore is controlling that market.
“It is controlling the lithium market.
“They have a substantial share of the copper smelting market, which has driven the rest of global copper smelters into complete disarray with negative TC/RCs [treatment and refining charges] over the past couple of years. And I think we will continue to see that.
“And that is very much about subsidising through the value chain. It’s about supporting national champions that are going out and putting their foot on resources globally and subsidising processing and concentrating in China.
“I don't think anybody else comes close to having that type of control and long-term strategy.”
The approach certainly contrasts with what is happening in, say, Europe where, according to Albemarle’s vice president of public affairs for the region, Francesco Gattiglio, support for designated strategic projects still exists mainly “on paper”.
“We do not really see strong financial support for these projects to be launched and if we are not ready to do whatever it takes to launch and support what we deem strategic then it is not a strategic project,” he said.
What does control of mining and metals look like in the third decade of the 21st century?
ICMM CEO Rohitesh Dhawan said US copper use was set to double to four million tonnes per annum within a decade, “yet the country has just two operating smelters”. China had 200. “How is it that the world’s largest economy – with the world’s most predictable long-term copper demand – cannot secure supply of a metal it considers essential? The answer is brutally simple: economics,” Dhawan said.
“A metal deemed critical, with soaring demand and high prices, is still starved of new mines and smelting capacity. The situation in Europe is arguably even more dire.
“And this reveals the uncomfortable truth: Western free-market rules are clashing with state-directed competitors. Governments must choose—embrace industrial policy or accept ongoing vulnerability.”
Head of metals and mining consulting at Wood Mackenzie, Patrick Barnes, said the world was consuming about 28Mtpa of copper a year, including 23Mtpa from mines and 5Mtpa from recycled supply, and was staring at circa-6Mtpa of new demand by 2035. “You’re talking about bringing on more than another Chile [5.5Mtpa] or more than another Africa [5Mtpa] and making it operational in the next 10 years. Not a small task.
“[Our] data would say that a lot of more supply has to come from the Americas than it has in the last few years, but if you look at what’s happened since 2019 something like $70 billion has been spent on new copper mines and over half of that was Chinese capital. Almost 20% of it was Russian and Caspian capital. The rest of the world financed about 30% of the mines.
“[China] has increased their share of global mining supply from 10% 15 years ago to 20% now. That's a huge gain of share in just 15 years.
“We have talked mostly about Chinese dominance at the processing stage but in copper they’re making massive inroads at the mining stage as well.”
Juan Ignacio Diaz, CEO of the International Copper Association, said copper had been elevated to critical mineral or raw material lists in many countries, the US only recently. The aim was to unlock public permitting and financial benefits: “We’re about to see. But that’s the intention.”
China didn’t designate copper as a critical mineral. “But they embedded it into the industrial policy. They don't say it but they act on it,” Diaz said.
Evy Hambro, global head of thematic and sector investing at $13.5 trillion asset manager, BlackRock, said China ignited then leveraged the last minerals boom. “When you think about the digital age that we’re going into very rapidly it is going to take more and more of these materials to allow countries to be competitive in that digital age.
“Governments are setting prices, they’re underwriting projects, they’re even beginning to put capital directly into equity, all in the name of security. There is an affordability question for governments: can they afford to pay more for something than it is worth?”
The answer, of course, was yes. “When you have got the scale and size of the US economy then ... rare earths are less than a rounding error,” Hambro said.
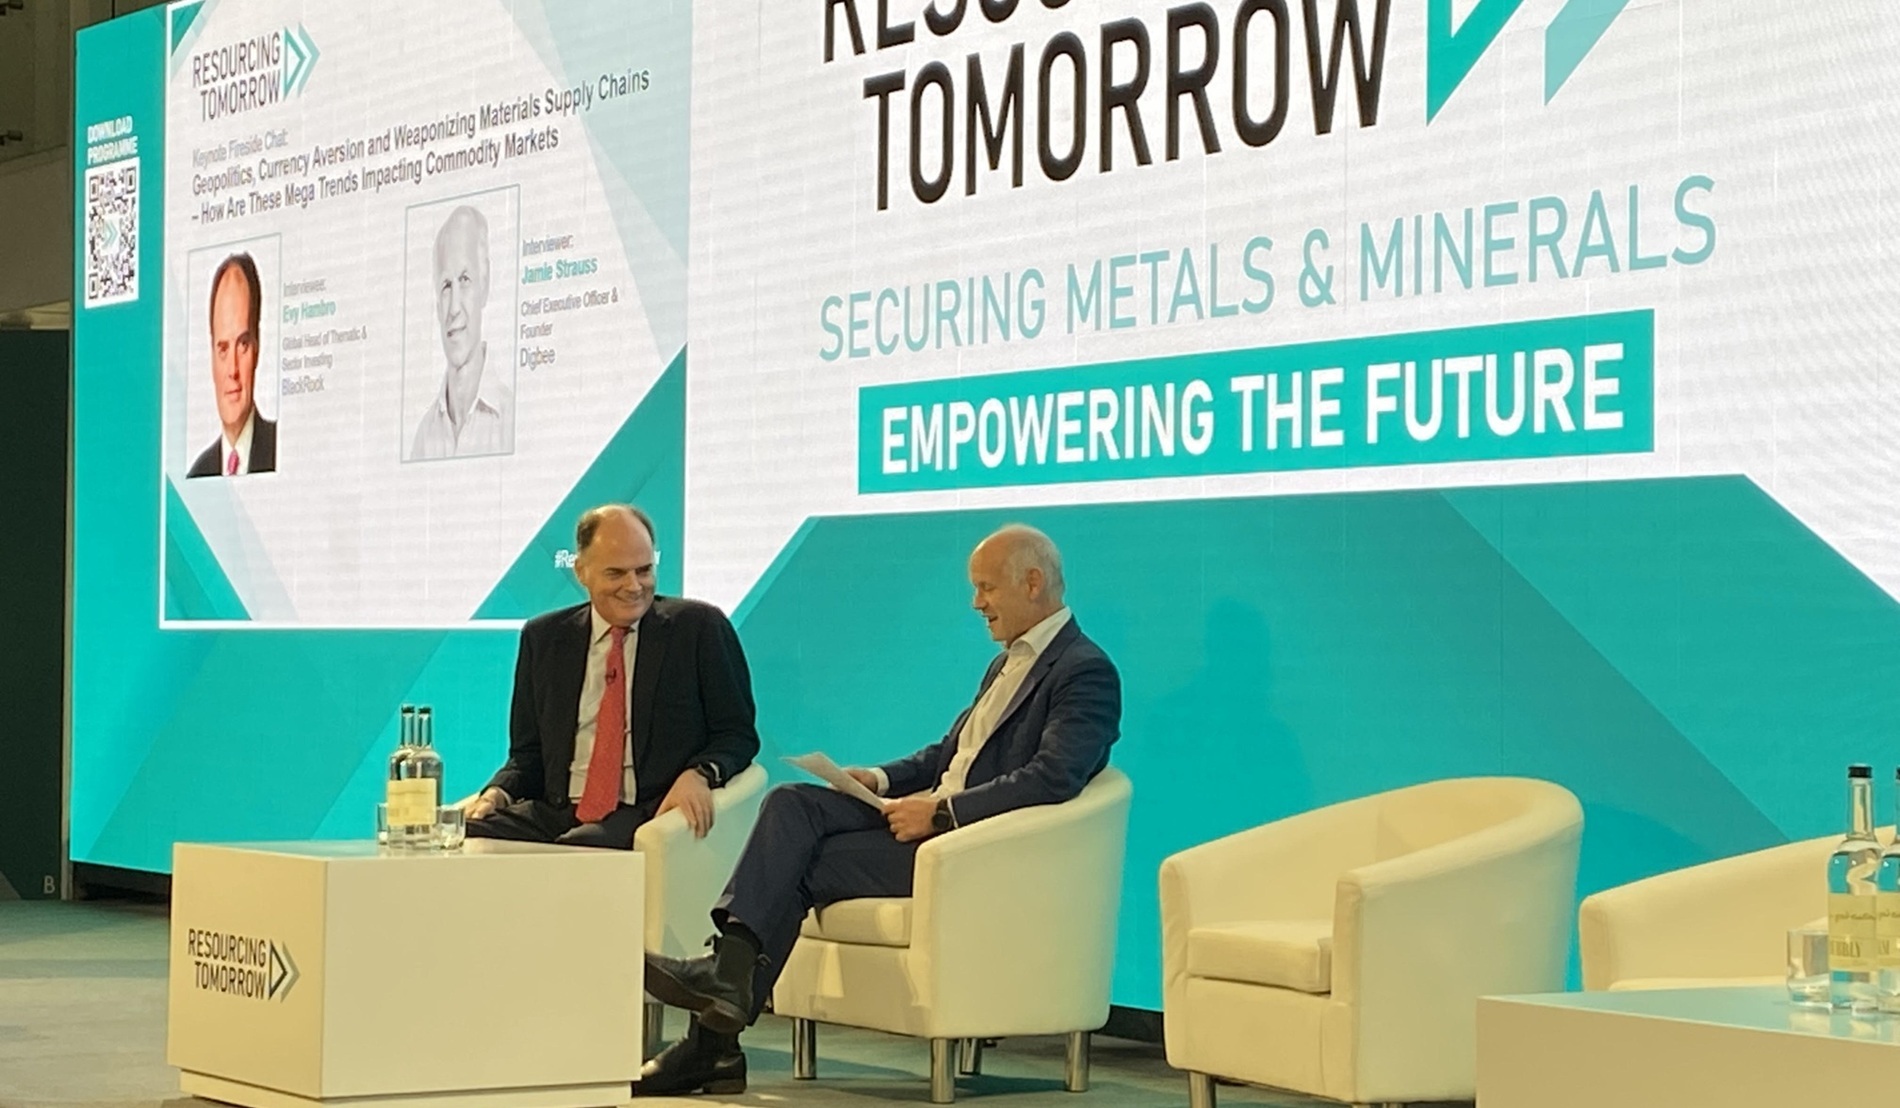
“If you think being the first or the biggest in AI is important then countries are going to pay anything to ensure that.
“But it is not just about that. It’s also about the true cost of delivered, reliable power and China has massively expanded its power generation. If it continues to expand faster and the developed world is stuck in red tape and planning bureaucracy, the investment needed to catch up will be slowed.
“So if it is a power race that delivers AI, China’s way out in the lead.”
A long history of short-termism
China’s long-term strategic manoeuvring was a major focus of conference talk but so, too, were other forces that have shaped the mining, metals and industrial landscape of today – and the road ahead.
Danilyuk said a decade or so ago big Western miners were divesting copper assets and Chinese groups were among the buyers. The “Great Garage Sale” of the period was heralded as portfolio optimisation, “but really it was to shore up highly stretched balance sheets”. Now diversified majors were “trying to figure out an angle to get more copper into their portfolios”.
The $53 billion Anglo American-Teck Resources deal, offering rare, real operational synergies in South America, is the headline act. Other deals will almost certainly follow.
“The issue is that the relative valuations have diverged very, very dramatically,” Danilyuk said.
“When I compare diversifieds versus pure-play copper producers the relative valuations differ by about two turns of EBITDA, which is massive and makes pure-play copper unaffordable for the diversified producers. A year ago the gold majors would have been competition for a transaction like this [Anglo-Teck]. Today it would be awfully difficult for a gold-focused major to make the argument that they're diversifying into copper given where gold prices are today.
“But do I see substantial new large-scale, M&A coming from diversified majors in order to build out their copper portfolios? I think it would be awfully difficult.
“They are in a pickle in the sense that organic growth is slow and long and difficult. It is either geopolitically fraught or stakeholder fraught. Witness Resolution [copper in the US] which has been stuck in a permitting morass for the better part of the past decade.
“Organic growth is difficult, inorganic growth is expensive, so while everybody is running the slide rule over one another, significant moves are going to be difficult to make.”

Mark Gupta, vice president – corporate development with Toronto-headquartered Hudbay Minerals, believes buy-versus-build continues to be top of mind for mid-tier and major mines while the “risks to developing projects [remains] very challenging”.
“WoodMac’s incentive price today is about $4.25 a pound for new projects. We're sitting at $1 a pound above that and you’re not seeing a whole wave of copper supply coming on,” he said.
“Either companies aren’t believing in the spot price or there's just not enough organic projects in the pipeline to actually be developed. So I think M&A is the natural progression. And clearly Anglo went through all those permutations to come up with the Anglo-Tech deal.”
From an Anglo perspective, group head of strategy Paul Gait said: “The basic problem here is the change in capital intensity is rising faster than the price of copper itself or a decline in the cost of capital. Those two things essentially need to reverse.
“Either the cost of capital has to be falling in percentage terms faster, the copper price has to be rising or the capital intensity of these mines needs to be falling.
“In the last wave of really explosive growth in the copper industry that’s of course what was happening.
“The capital intensity of the mines was declining because there was technological innovation that was coming to the fore that was allowing that to happen.
“Where is the new technology? Where is the innovation that can act as a deflationary driver?”
Dhawan said the industry should be in a golden age of innovation. “Mining has never needed innovation more,” he said. “Permitting is slow. Environmental and social expectations are rising. Demand is surging. Companies are pledging low-carbon, nature-positive, minimal-waste mining.
“[But] every innovator I’ve spoken to in the past year tells the same story: Our solution improves safety, efficiency or both. We’ve proven it works in real conditions. But we cannot get companies to bring us on site.
“This is cultural work – deep, long-term, values-driven change. And it needs to start now.”
Darryn Quayle, UK resources vice president of heavyweight engineering firm Worley, told the conference: “We need to get out of our comfort zone and embrace innovation while finding ways to share or mitigate the risks of being early adopters. That’s the only way to shrink mining’s environmental footprint and earn the public’s trust on a grand scale.”
The conference heard community, investor and Gen Z trust deficits, magnified over time despite mining’s safety, environmental and material social improvements, were all contributing to project delays and ultimately cost escalation at a time when the industry was trying to replace ageing production assets and long-term profit engines, and build new mines.
Adam Burstein, strategic and critical materials technical director in the US Government defence secretary’s office, said minerals were making regular headlines in America, possibly for the first time in generations. Paradoxically, though, Burstein doesn’t think government or industry are “doing a good enough job with public messaging”.
“We’re seeing this become a more focused issue globally,” he said.
“But until we have buy-in from the citizenry writ large to mobilise industry, to mobilise capital, to mobilise natural resource treasure to address these issues, I think we’re going to fall short.”
James Hartop, partner at US investment bank Centreview Partners, said: “Interestingly when you look at the world’s top 20 undeveloped copper projects the biggest single problem isn't actually the copper price. It's the social license. It's not having the license and the community support.
“For sure there is a financing issue. But it also goes around how conditions can be changed to facilitate new developments. Simply standing back and hoping that everyone recognises the urgency, and therefore we should get the licences, isn't going to work. If you’re living right next to a prospective copper development you couldn't really care less about that and you’re going to keep the pressure on not to develop.”
Hartop said a critical need for patient capital in mining was growing as “the timescale of projects is getting longer and longer”. He described that as an acute problem because typical investors were “forced to perform month-to-month and quarter-to-quarter, yet the [mining] capital cycle is getting longer and longer”.
“The funding model needs to find different ways of getting it done. There needs to be thought around models of syndicating risk. From the shareholder perspective, returns are going to happen over time. There may need to be a change in the mix of capital allocation; maybe less on the short term, more through the growth. And there needs to be real discipline around the projects in development.”
If off-again consolidation is on again, offshoring – of mineral processing and manufacturing, mainly to China – has also changed direction.

Dominic Raab, the former UK deputy prime minister now heading global affairs at Appian Capital Advisory, said “friend-shoring” was “very much the challenge of our time and probably one of the three essential elements to reviving, or providing, the ex-China supply chains the West needs”.
“The first being capex and the second being better public/private partnerships,” he said.
“Almost all jurisdictions talk about onshoring as much as they can and there's clearly value in that in terms of jobs and trade deficits. But in terms of supply chain security our advice when we talk to sovereigns and international institutions is you probably want to onshore when you can but friend-shore when you must.
“Most governments will inevitably start to develop a hub and spoke model.”
Former US assistant secretary of state for energy resources Geoffrey Pyatt said mining and metals public-private partnerships were proliferating and would require long-term support from predominantly two-party Western democracies.
“One risk of our democracies, and it happens as much in the United States as in the UK, is we're constantly reinventing things because ministers and political leaders like to have announcements,” said Pyatt, who joined Washington-based McLarty Associates as senior managing director, Energy & Critical Minerals, earlier this year.
“One of the things that I’ve learned working now in the private sector is that CEOs like continuity and predictability and so there’s a disconnect between our four-year election cycles in the US and industry, which is characterised by decades-long investment horizons.
“Managing that tension [is key].
“It took us several decades to get into this hole and it’s going to take us a couple of decades to get to a situation of geopolitical security around minerals.”


